
News & AnalysisCareer

With interest rates expected to stay unchanged, the Bank of Japan (BoJ) is due to deliver its monetary policy decision at around 02:30 GMT on Friday.
Following a 25 basis points (bps) increase at its September policy meeting, the BoJ’s interest rate stands at 1.25%, Japan’s highest level in 31 years. Financial markets are confident that rates will be held there, mirroring expectations for the Federal Reserve (Fed). The BoJ has raised rates twice this year, by a quarter of a percentage point on each occasion.
In a note, Commerzbank said markets anticipate “the overnight rate remaining steady, and none of the economists surveyed by Bloomberg expects a hike on Friday”. With that consensus in place, investors will look instead to the monetary policy statement, the central bank’s outlook report and Governor Kazuo Ueda’s press conference for guidance on policy through to year-end.
Since the September policy meeting, BoJ Governor Ueda has voiced concern over inflation risks stemming from energy prices. Alongside repeated assurances that monetary tightening will continue, he has emphasised the need to anchor core inflation close to the 2% target.
FXStreet’s Speechtracker assigned Ueda’s 16 October speech a score of 8.2/10, above his average of 7.5 and pointing to a modestly more hawkish stance. Underlying inflation is “quite close” to 2%, Ueda stressed, while developments in the economy and prices remain broadly consistent with forecasts. His pledge to “continue to raise interest rates” while financial conditions remain accommodative, together with plans to discuss revising the assessment of inflation’s progress towards 2%, reinforced a bias towards gradual normalisation, supporting a firmer Yen.
On AI-driven inflationary pressures, Ueda said there was “no big gap” between the Bank of Japan’s assessment and those of global policymakers, although some counterparts were more optimistic about AI demand. Those remarks highlight upside price risks that warrant retaining the option of further tightening. By linking the pace and timing of future rate increases explicitly to FX, AI demand and developments in the Middle East, Ueda set out a policy response sensitive to both data and risks. That approach offers incremental support for the Japanese Yen, particularly if AI-related demand and external shocks keep inflation around the 2% target.
Taken together, the remarks suggest that the BoJ’s Ueda will retain a hawkish policy outlook, stressing the need to anchor price pressures close to the central bank’s 2% target.
Nearly 70% of economists, or 54 of 78, expected the BoJ to increase its policy rate to 1.5% this quarter in the Reuters poll conducted on 13-19 October, Reuters reported. That proportion was almost twice the share in the previous survey, with the consensus pointing to a further rise before year-end.
With market participants firmly expecting unchanged policy rates, the BoJ’s decision itself looks unlikely to be a significant event for USD/JPY. Instead, the tone of its monetary policy outlook and any indications of where policymakers see the terminal rate are likely to matter.
A signal that the BoJ could reach its terminal rate sooner would support the Japanese Yen (JPY). By contrast, guidance pointing to a gradual tightening path could leave the currency little changed. On balance, this leaves USD/JPY risks moderately skewed to the downside.
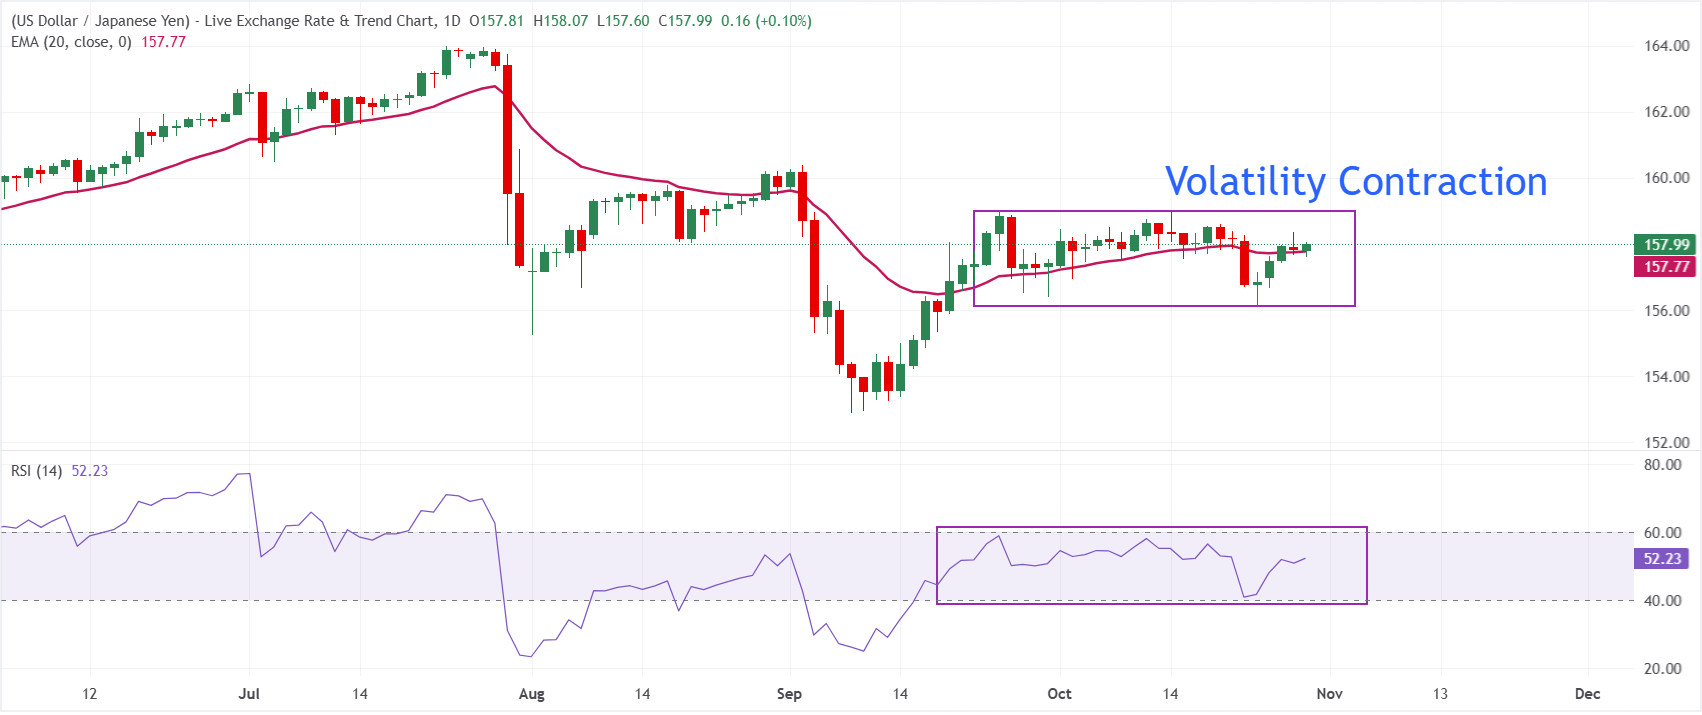
Trend: A flat 20-day exponential moving average (EMA) at 157.77 points to a sideways trend, with USD/JPY trading around 157.80 at the time of writing. For more than a month, the pair has been confined to a range bounded by 156.08 and 159.04.
Momentum: A month within the 40.00-60.00 band for the Relative Strength Index (RSI) signals a pronounced contraction in volatility, lending further weight to the ongoing consolidation.
Support: The range floor at 156.08 provides the first downside support. Failure to defend 156.08 would leave the pair vulnerable to a move towards the 14 September high of 155.00.
Resistance: The consolidation ceiling near 159.04 marks the immediate barrier to gains. A convincing move above it would make a further advance towards 160.00 more likely, with the September high near 160.40 next in view.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Responsibility for setting Japan’s monetary policy rests with its central bank, the Bank of Japan (BoJ). Its mandate covers issuing banknotes and managing currency and monetary conditions to maintain price stability, defined as an inflation target of around 2%.
Against a backdrop of low inflation, the Bank of Japan adopted an ultra-loose monetary stance in 2013 to bolster economic activity and lift price growth. Quantitative and Qualitative Easing (QQE) forms the basis of that policy: banknotes are printed to purchase assets, including government and corporate bonds, and inject liquidity. The bank stepped up its approach in 2016, easing further through the introduction of negative interest rates followed by direct control of the yield on its 10-year government bonds. A rate increase in March 2024 effectively marked the BoJ’s retreat from its ultra-loose stance.
Large-scale stimulus from the Bank weakened the Yen against its major currency peers. In 2022 and 2023, that depreciation intensified as the policy gap widened between the Bank of Japan and other leading central banks, which raised rates sharply to tackle inflation at multi-decade highs. The BoJ’s stance widened interest rate differentials with other currencies, weighing on the Yen’s value. The currency partly reversed that trend in 2024 following the BoJ’s decision to move away from ultra-loose policy.
Japanese inflation climbed above the BoJ’s 2% target as the Yen weakened and global energy prices surged. Expectations of higher domestic salaries, a key driver of inflation, also helped prompt the decision to begin unwinding ultra-loose policy.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


