


The Canadian Dollar round-trips as Fed officials differ on hike timing
- USD/CAD tops 1.4200 for the first time since early July, slips on Fed talk.
- BoC pushes its first bond purchases out to late 2027, possibly 2028.
- US core PCE seen rising 0.3% MoM on Wednesday, up from 0.2%.
Tuesday's two Canadian catalysts, a flat July for the economy and a later start to Bank of Canada (BoC) bond buying, didn't move USD/CAD. The pair went above 1.4200 for the first time since early July and fell back twice. The second drop began when New York Fed President Williams, a permanent voter on rates, said there's no rush to hike again. The BoC's news came from a conference stage in Manhattan, and the Fed speech that moved the Loonie was given in Buffalo, a short drive from Ontario.
No urgency still means one more hike this year
US job openings fell to 7.079 million in August against a 7.23 million forecast, and USD/CAD recovered the dip before Fed Governor Barr spoke. The pair made its second run at the session high after Governor Barr said in Detroit that high energy prices and artificial intelligence investment mean more hikes are likely needed. President Williams said one more hike may be appropriate late this year and that the September 16 move to 3.75%-4.00% gives the Fed time to wait for data.
Fed funds futures still price about a 70% chance of an October hike, which leaves most of the case for a higher USD/CAD in place. The timing matters because both central banks decide on October 28. A BoC hike on a day the Fed holds is the outcome that narrows the gap between their rates. President Williams doesn't see inflation back at the Fed's target until 2028, and sees no need for urgency.
The economy stalls on schedule and BoC bond buying slips again
Statistics Canada said the economy was flat in July, exactly as forecast, after 0.4% growth in June. Construction rose 1.3%, with non-residential building having its best month since early 2022 on work at a new Toronto hospital, and utilities rose 1.7% in a heat wave. Together they offset declines led by a 0.9% drop in manufacturing.
Statistics Canada's early estimate for August is 0.2%, and National Bank of Canada estimates that leaves the third quarter tracking near 2.0% annualized, ahead of the BoC's 1.5% forecast. BoC Governor Macklem said on September 2 that the BoC was prepared to raise rates more than once if inflation stayed too high. Swaps price a little better than even odds of a hike on October 28, and a quarter running ahead of forecast is part of the case for it.
The BoC said during Deputy Governor Gravelle's appearance at a Bloomberg conference in New York that its Government of Canada bond buying could start in late 2027, or possibly 2028. In November 2025 the BoC said the purchases likely wouldn't need to start until 2027. Bond buying of this kind is routine upkeep, not stimulus, so a later start changes who holds Canada's bonds rather than the BoC's rate. Deputy Governor Gravelle once put the start at the end of 2026, at the earliest.
The Fed's October call could come down to a tenth of a point of core PCE
Core Personal Consumption Expenditures (PCE) prices, the Fed's preferred inflation gauge, are forecast to rise 0.3% MoM in August after 0.2% in July, with the YoY rate steady at 3.3%. The release is due Wednesday at 12:30 GMT, with headline prices seen up 3.7% YoY and personal spending forecast to rise 0.8% after 0.2%. A 0.3% on core would keep an October Fed hike priced, and anything softer would raise the odds of the Fed holding on October 28, the day the BoC may hike.
Canada's next release, the S&P Global Manufacturing Purchasing Managers Index (PMI), is due Thursday at 13:30 GMT after 53 in August. A Canadian reading slipping toward 50 would echo July's manufacturing drop and weaken the BoC hike case. The Institute for Supply Management (ISM) manufacturing PMI follows at 14:00 GMT, forecast at 55, with its prices component seen at 72.3.
Friday's payrolls are forecast at 90K, with unemployment at 4.1% and average hourly earnings up 0.3% MoM. A payroll number at or above forecast on top of a 0.3% core reading would keep October's hike priced and the run in USD/CAD intact. August's 162K came in at almost three times its forecast and lifted the odds of the September hike. Friday's release revises it, so the Fed gets a second look at evidence it has already acted on.
Technical levels
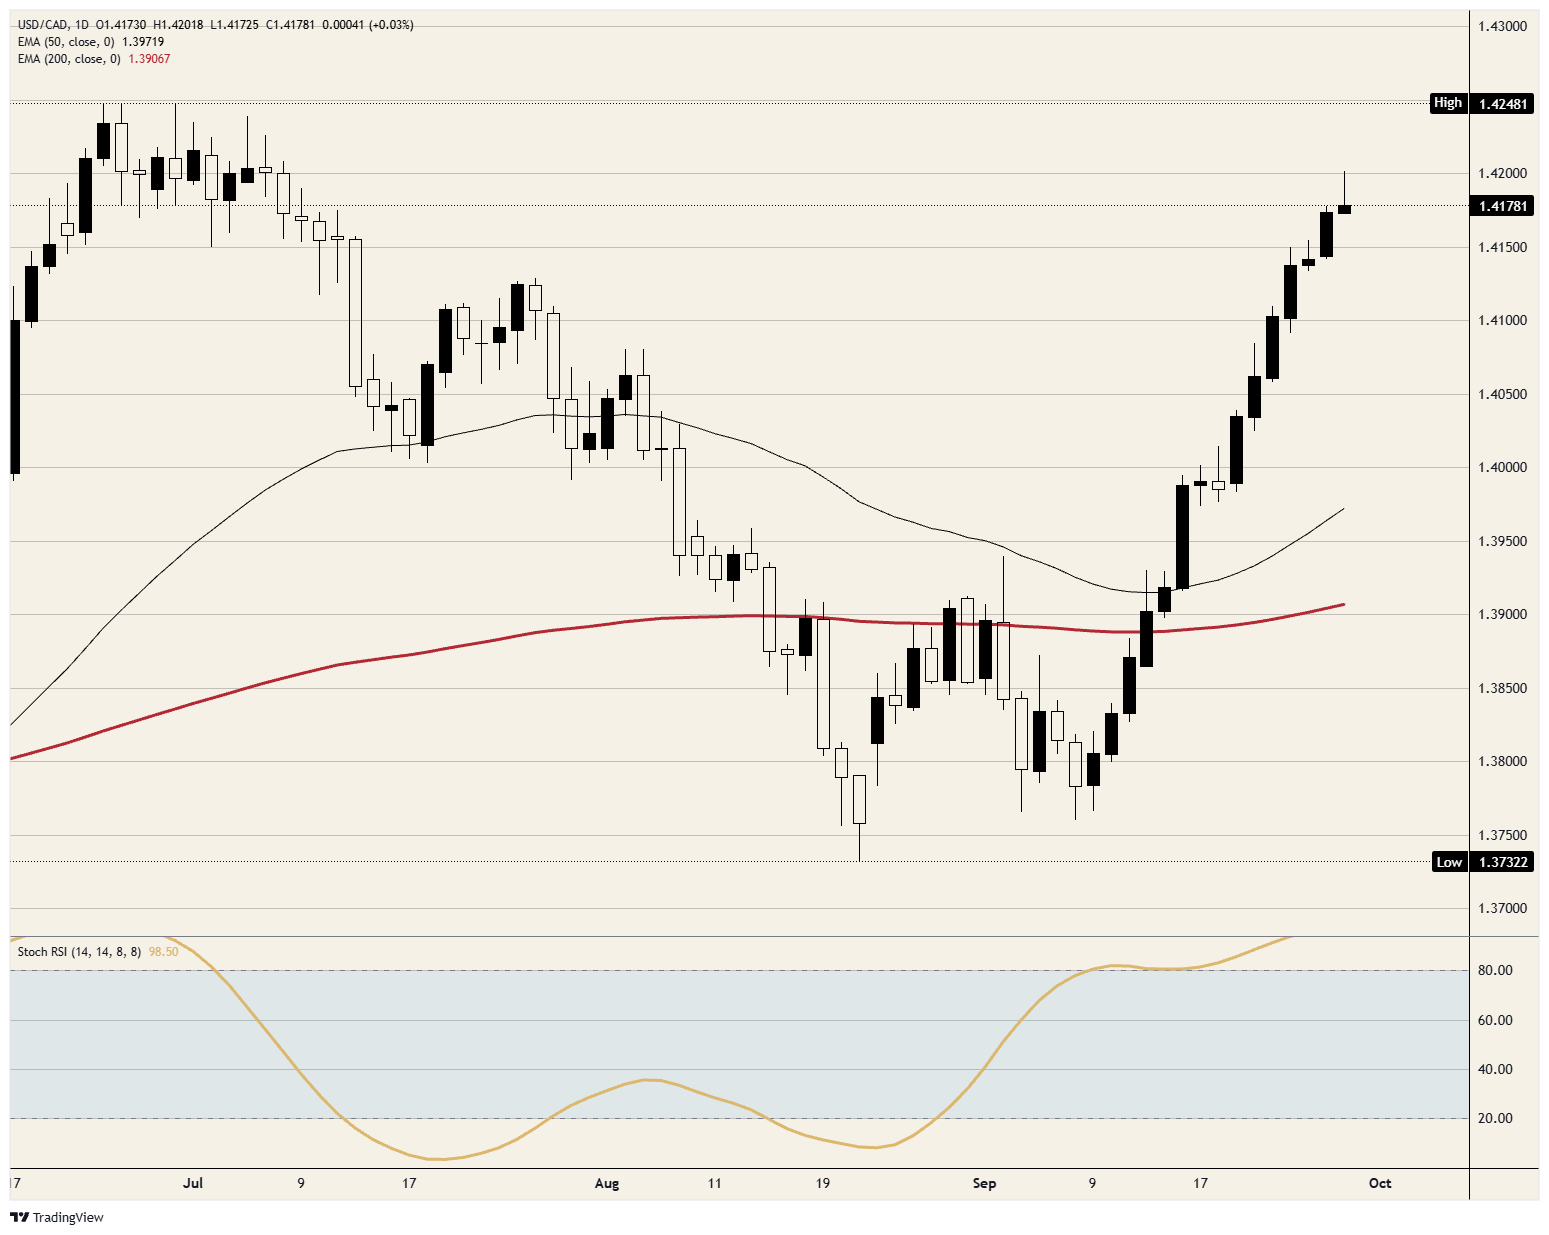
Resistance: 1.4200 stopped USD/CAD twice on Tuesday, and the session high just above it is the pair's first trade over that level since July 8. The late-June high near 1.4250 is the top of the range the pair left in mid-July.
Support: Monday's sixth straight daily gain went through 1.4150, which makes it the first floor. September 24's low just under 1.4100 is the run's most recent pullback low.
Bias: Long while 1.4100 holds on a closing basis, with 1.4250 as the first objective and 1.4300 as the second. A dip into 1.4150 wouldn't change the call, since the daily Stochastic Relative Strength Index (Stoch RSI) is near 98 and has almost no room left to rise. A daily close under 1.4100 ends the long.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
인기 기사
1United States API Weekly Crude Oil Stock dipped from previous 1.786M to 1.019M in September 252What will drive crypto prices? WisdomTree on the role of adoption and revenue3Gold springs from $4,110 as Oil rout eases inflation heat4The Canadian Dollar round-trips as Fed officials differ on hike timing5Fed’s Williams says worst inflation shocks have passed6United States Dollar Index approaches yearly peak on hawkish Fed outlook7Fed’s Williams says no rush after September hike8Fed’s Goolsbee says persistent inflation is like “playing with fire”9Forex Today: Focus shifts to US PCE, ADP, inflation in OZ and Chinese PMIs
실시간 시세



소셜 미디어












이 웹사이트에 제공된 정보는 일반적인 성격의 정보일 뿐이며 개인 맞춤형 금융 자문을 구성하지 않습니다. 이 웹사이트의 정보를 바탕으로 행동하기 전에, 귀하의 목표, 재정 상황 및 필요에 비추어 해당 정보의 적합성을 고려해야 합니다. CFD 및 FX 마진 계약에 대한 투자는 상당한 위험을 수반하며 모든 투자자에게 적합하지 않을 수 있습니다. 귀하는 최초 예치금보다 더 큰 손실을 입을 수 있습니다. 귀하는 기초자산에 대한 소유권이나 어떠한 이해관계도 보유하지 않습니다. 거래를 시작하기 전에 독립적인 자문을 구하고 관련 위험을 충분히 이해하시기를 권장합니다. 웹사이트에 기재된 상품을 취득하기 전에 공시 문서를 읽고 검토하는 것이 중요합니다. 이 웹사이트에서 제공되는 정보 및 광고는 그러한 사용이 현지 법률 및 규정에 위배되는 국가 또는 관할권의 개인이 사용하도록 의도된 것이 아닙니다. 이 웹사이트에서 제공되는 상품 및 서비스는 미국, 말레이시아 및 태국 거주자를 대상으로 하지 않습니다.
TMGM은 다양한 관할권에서 승인 및 규제를 받고 있습니다.
TMGM으로 거래하는 Trademax Australia Limited는 호주 증권투자위원회(ASIC)의 규제를 받으며, AFSL 번호 436416이고 Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia에 위치하고 있습니다.
이메일: support@tmgm.com.au
TMGM으로 거래하는 Trademax Global Limited는 바누아투 금융서비스위원회(VFSC)의 승인 및 규제를 받으며, 등록 번호 40356이고 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu에 등록되어 있습니다.
이메일: support@tmgm.com
Trademax Global Markets (SE) Limited(이하 TMGM)는 세이셸 금융청(FSA)의 인가 및 규제를 받으며, 허가 번호는 SD224입니다. 회사는 세이셸 마헤, 프로비던스 에스테이트 ABIS 센터, 사무실 번호 13에 등록되어 있습니다.
이메일: support@tmgm.com
TMGM으로 거래하는 Trademax Global Markets (International) Pty Ltd는 모리셔스 금융서비스위원회(FSC)의 승인 및 규제를 받으며 라이선스 번호 GB22201012이고, 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius에 등록되어 있습니다.
이메일: support@tmgm.com
Copyright © TMGM. All rights reserved