

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
BoJ minutes lift Yen as Ueda and US NFP take focus on Friday
- Below 158.00 again, USD/JPY has returned to levels seen before Tuesday's surge towards 159.00.
- December rate-hike expectations strengthened after the BoJ minutes, while US technology shares declined.
- Friday brings US payrolls data alongside a speech from BoJ Governor Ueda.
USD/JPY has retreated to just above 157.50. Tuesday's peak, just below 159.00, was its highest since mid-October. The Yen is strengthening on Thursday even as the Dollar advances against the Pound, Euro, Kiwi and Aussie. Bank of Japan (BoJ) minutes, interpreted as supporting a December rate rise, drove the Yen's gains, with falling US technology shares providing additional support.
An eight-to-one vote kept the BoJ's rate at 1.25% on 30 October, while board member Takata favoured 1.5%. Its next meeting is on 17-18 December. Thursday's minutes highlighted that division. The gap between the BoJ rate and the Fed's 3.75%-4.00% stands at two and a half percentage points or more. Provided the Fed holds rates steady, a December BoJ increase would narrow the gap by a quarter-point.
Markets assign a probability of nearly 70% to a Fed rate rise on 9 December. On Thursday, Cleveland Fed President Hammack said policy needs to become restrictive, having voted for an increase on 28 October. If Washington raises rates on 9 December and Tokyo follows on 18 December, the differential would remain unchanged. Thursday's decline in US technology shares is also contributing to the Yen's strength.
December decisions: data and speeches ahead
A 3.8% year-on-year increase is forecast for Japan's September labour cash earnings, matching August's pace. The figures are due at 23:30 GMT on Thursday. BoJ Governor Ueda will speak on Friday at 16:00 GMT. Both will inform the BoJ's 17-18 December decision, its final one this year.
October Nonfarm Payrolls (NFP), due on Friday at 13:30 GMT, are expected to rise by 65K, following September's 29K increase. Earlier that day, New York Fed President Williams is scheduled to speak at 09:30 GMT. The October Consumer Price Index (CPI) follows on Tuesday, 10 November, at 13:30 GMT. A 0.3% reading is forecast, down from 0.6%, with the release informing the Fed's 8-9 December meeting.
156.00-159.00 range back in focus
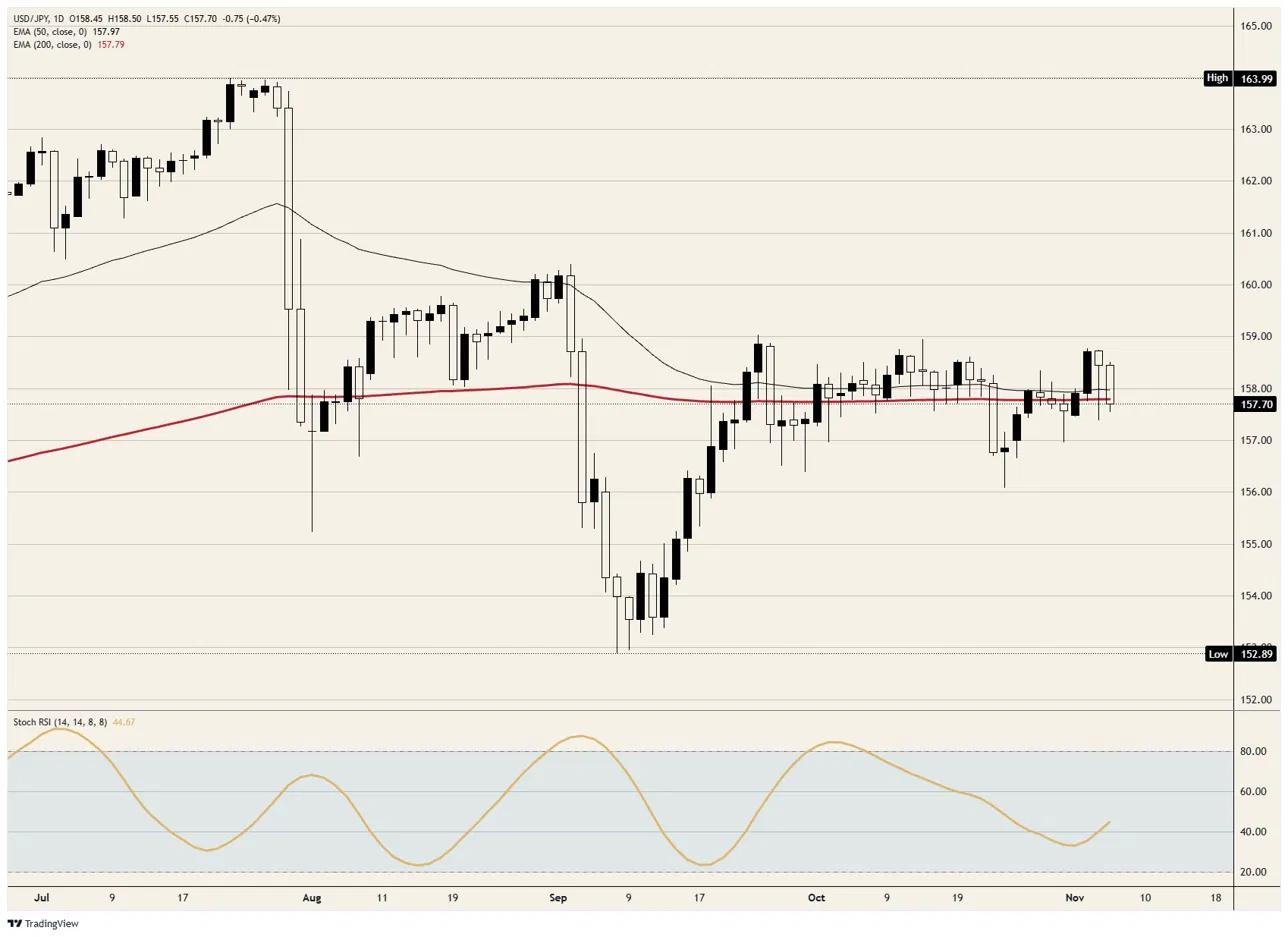
Since late September, USD/JPY has remained within a 156.00-159.00 trading range, which it has now re-entered. Tuesday's peak marked another reversal from just below 159.00. Both the 50-day Exponential Moving Average (EMA) and the 200-day EMA sit within a quarter-Yen of 158.00. The pair is trading slightly beneath both averages.
USD/JPY: daily price chart
Japanese Yen: frequently asked questions
Among the world's most actively traded currencies, the Japanese Yen (JPY) broadly reflects the performance of Japan's economy. More specific influences include Bank of Japan policy, the gap between Japanese and US bond yields, and traders' appetite for risk, alongside other factors.
Currency control is part of the Bank of Japan's mandate, making its actions important for the Yen. Direct intervention in foreign exchange markets has occasionally been used, usually to weaken the currency. Political concerns among Japan's main trading partners, however, discourage frequent intervention. Between 2013 and 2024, the BoJ's ultra-loose monetary stance weakened the Yen against its major peers as policy increasingly diverged from that of other leading central banks. The more recent gradual withdrawal of that ultra-loose policy has provided some support for the currency.
By maintaining ultra-loose monetary policy over the past decade, the BoJ increasingly diverged from other central banks, notably the US Federal Reserve. That divergence helped widen the yield gap between 10-year US and Japanese bonds, supporting the US Dollar against the Japanese Yen. The differential is now narrowing as the BoJ implements its 2024 decision to gradually move away from ultra-loose policy and other major central banks cut interest rates.
Investors often regard the Japanese Yen as a safe-haven asset. During periods of market stress, its perceived stability and reliability make investors more inclined to move funds into the currency. Such turbulence is therefore likely to lift the Yen against currencies considered riskier investments.
POPULAR ARTICLES
1AUD/USD breaks 0.6950 as NASDAQ rout threatens key 0.6900 support2BoJ minutes lift Yen as Ueda and US NFP take focus on Friday3Below 0.5600 again: Kiwi heads into New Zealand’s Saturday vote4One-Month High Reversal: Euro Under Pressure Ahead of Friday's US NFP5Pound surrenders BoE rate-hike gains ahead of Friday's US payrolls6Banxico's surprise rate cut sends Mexican Peso sliding as easing bets grow77% ETH decline: Ethereum price forecast as AI sell-off pressures crypto8Data-centre backlash wipes out Dow Jones Industrial Average’s midterm rally9Chinese Yuan: Gains Capped by PBoC Resistance – Societe Generale


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved