

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Third straight RBNZ hike priced in by New Zealand Dollar traders
- 0.5700 remains out of reach at the close as NZD/USD stalls just above it for a fourth session.
- 3.50% is TD Securities' new RBNZ rate forecast after three hikes, but the Kiwi retreats.
- 3.00% is the expected RBNZ rate after Wednesday's hike, ahead of the election.
0.5700 remained above NZD/USD's closing level on Monday. For a fourth consecutive session, the pair stalled just above that threshold as traders bought US Dollars ahead of Wednesday's Fed decision. The decline came despite TD Securities abandoning its forecast for a Reserve Bank of New Zealand (RBNZ) pause in favour of three rate increases.
A quarter-point RBNZ increase to 3.00% carries a market-implied probability of nearly 90%. In a Reuters survey, 22 of 27 economists also forecast that outcome. With the increase already priced in, the Kiwi's prospects depend on the subsequent policy path. A further rise to 3.25% in December is expected by nine of 23 economists in the same poll.
At 3.7%, third-quarter inflation came in below the RBNZ's 3.9% projection. Economists nevertheless expect a rate increase: they see fuel costs and a softer Kiwi pushing inflation back above 4% in the fourth quarter. The currency's weakness therefore forms part of the argument for tighter policy.
3.00% in focus for Wednesday's RBNZ decision
At 01:00 GMT on Wednesday, the RBNZ will release its rate decision and Monetary Policy Review. The cash rate is forecast to increase from 2.75% to 3.00%. The announcement falls ten days before New Zealand's 7 November election. The central bank's own rate projections span the December and February meetings underpinning TD's forecast.
A 3.75%-4.00% range is expected to remain in place when the Fed announces its decision on Wednesday. Its statement is scheduled for 18:00 GMT, followed by Fed Chair Warsh's press conference. US rates would remain above the 3.00% expected for the RBNZ. Before then, Tuesday's September durable goods orders are forecast to show a 0.6% increase.
50-day EMA caps NZD/USD recovery
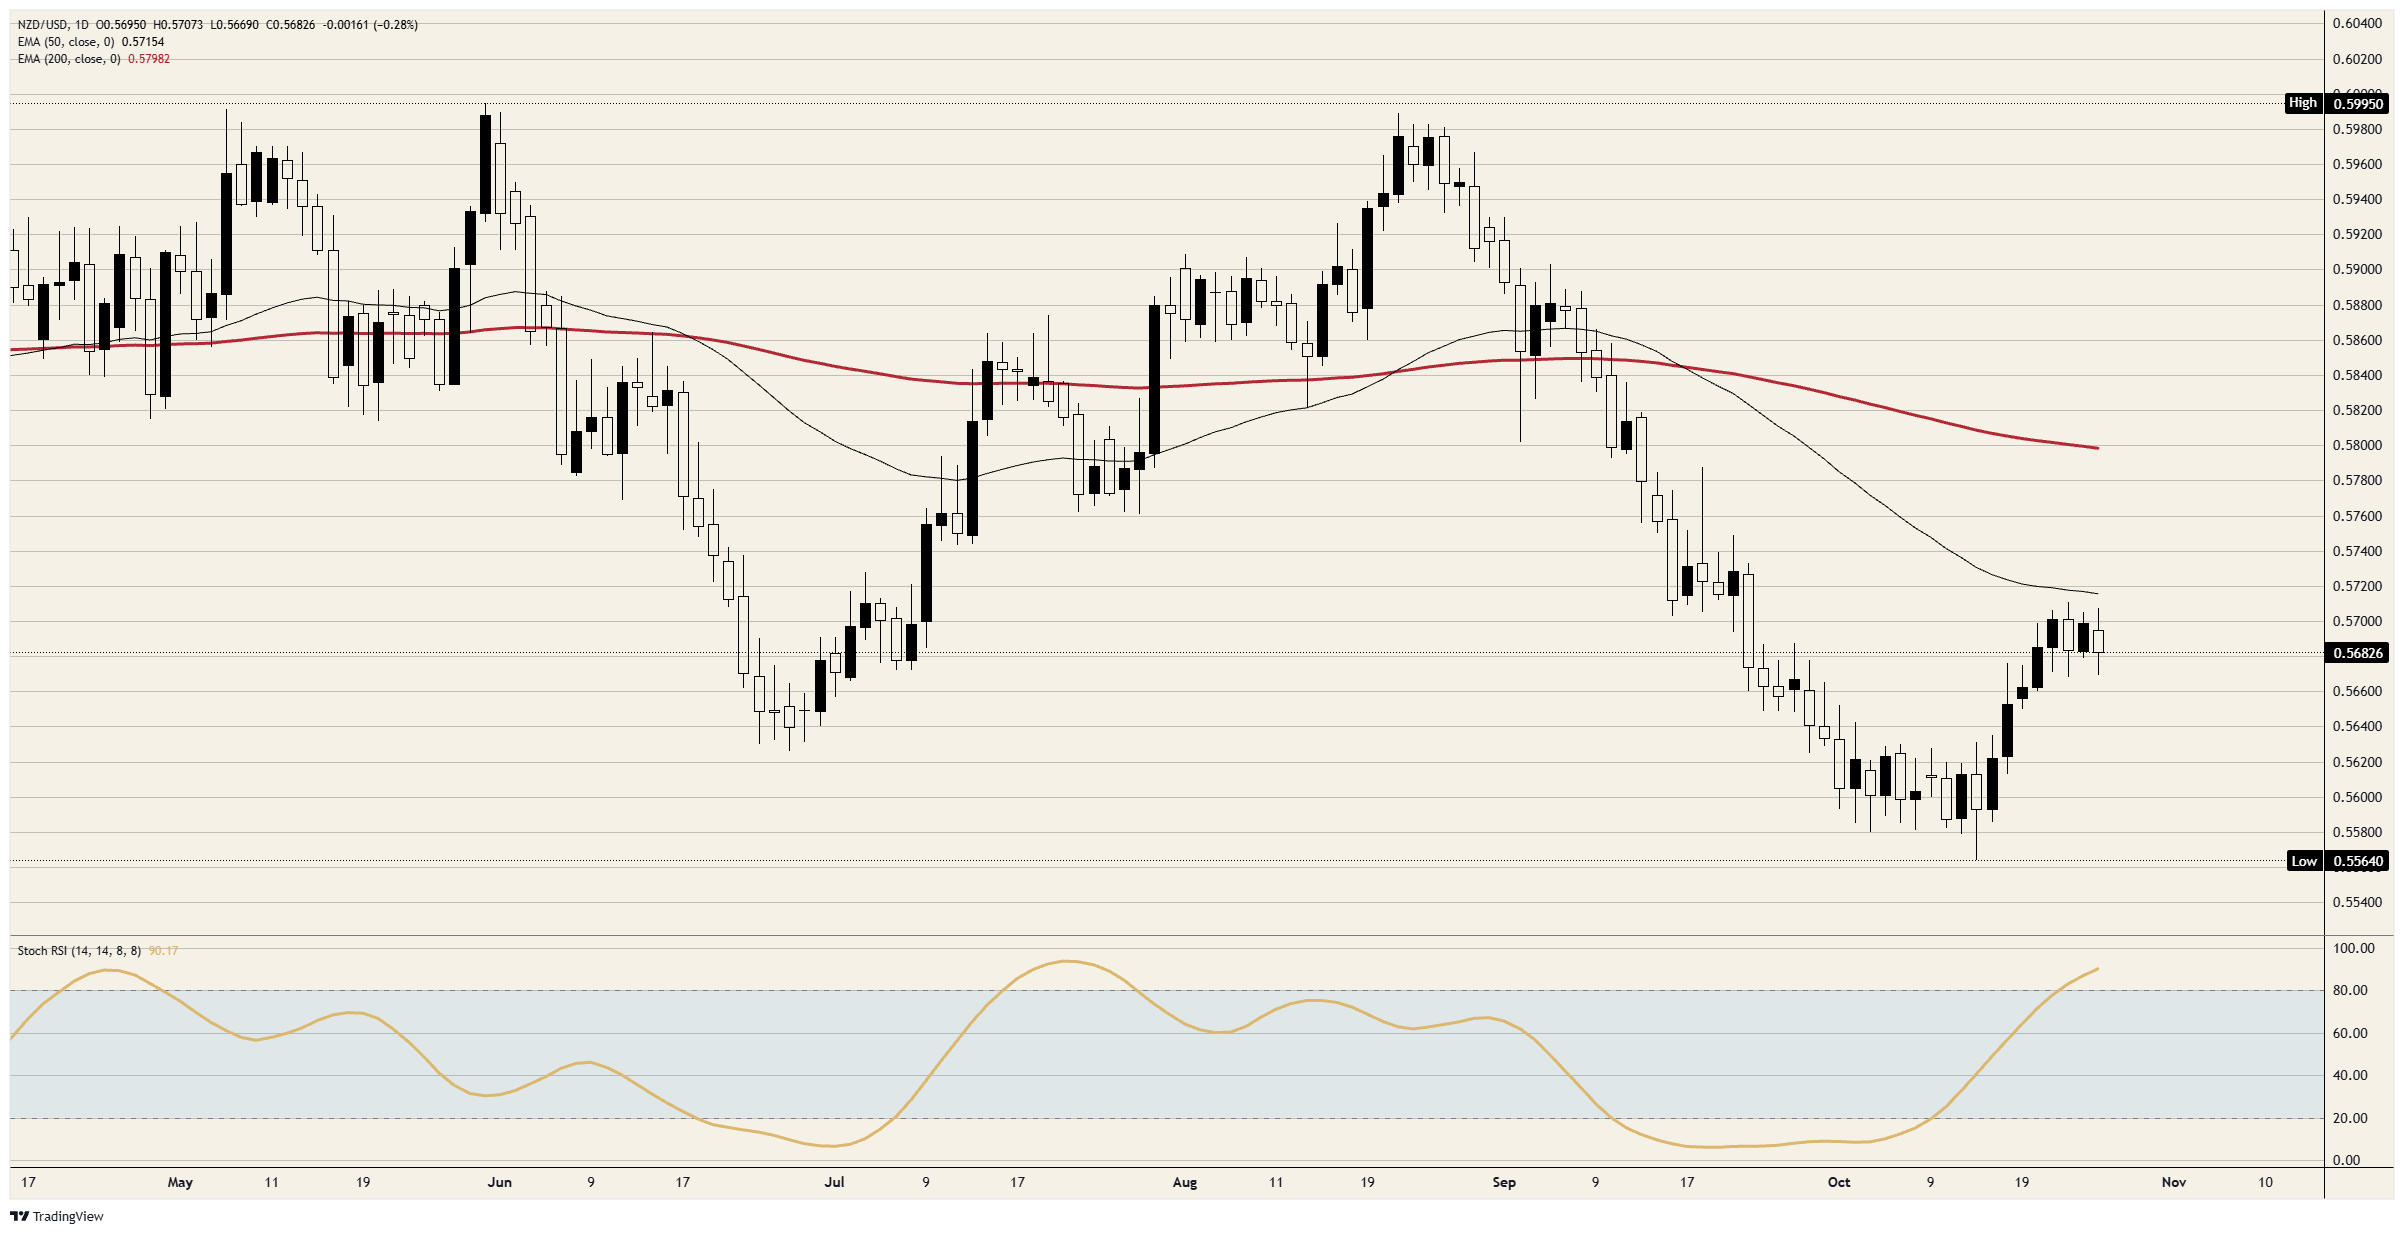
Below the 50-day Exponential Moving Average (EMA), NZD/USD's recovery from its 14 October low just above 0.5550 has lost momentum. The 200-day EMA sits just below 0.5800. About a fifth of the recovery was erased by Monday's decline, while daily momentum is overbought for the first time since late July.
NZD/USD: daily price chart
New Zealand Dollar: frequently asked questions
Known as the Kiwi, the New Zealand Dollar (NZD) is a familiar currency among investors. New Zealand's economic health and central bank policy largely determine its value, alongside several distinctive influences. China, the country's largest trading partner, is one such influence: developments in the Chinese economy tend to affect the Kiwi. Adverse Chinese economic news is likely to imply weaker demand for New Zealand exports, weighing on its economy and currency. Dairy prices are another driver, as dairy is New Zealand's main export industry. Higher prices lift export earnings, supporting both the economy and NZD.
An inflation rate of 1% to 3% over the medium term is the Reserve Bank of New Zealand's (RBNZ) objective, with particular emphasis on keeping it close to the 2% midpoint. The bank sets interest rates at a level appropriate to that goal. Excessive inflation prompts the RBNZ to raise rates to restrain economic activity. Higher rates also lift bond yields, making investment in New Zealand more attractive and supporting NZD. Rate cuts, by contrast, generally weaken the currency. NZD/USD can also be heavily influenced by the rate differential: the gap between current or expected New Zealand interest rates and those set by the US Federal Reserve.
New Zealand's macroeconomic releases help investors assess economic conditions and can alter the valuation of the New Zealand Dollar (NZD). Robust growth, low unemployment and strong confidence signal an economy that supports NZD. Strong growth draws foreign investment; when accompanied by elevated inflation, it may also prompt the Reserve Bank of New Zealand to raise interest rates. Weak economic figures, in contrast, are likely to lead to NZD depreciation.
When investors view broader market risks as low and are optimistic about growth, the New Zealand Dollar (NZD) generally appreciates. These risk-on conditions usually improve the outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Market turmoil or economic uncertainty tends to have the opposite effect: investors sell higher-risk assets in favour of more stable safe havens, typically weakening NZD.
POPULAR ARTICLES
1Half its gain erased: Yen retreats ahead of expected BoJ hold on Friday20.70 rally falters for Aussie Dollar ahead of Fed, RBA inflation tests3Third straight RBNZ hike priced in by New Zealand Dollar traders4Below 1.12: Euro faces Fed and ECB decisions a day apart5Pound retreats from its high ahead of UK Budget and Fed decision6Anthropic's filing boosts tech while Dow Jones Industrial Average trails7211.10 in bulls’ sights: GBP/JPY Price Forecast as bearish trend continues8Iran peace hopes buoy sentiment as Mexican Peso withstands Dollar strength9FOMC and Yields Shape Singapore Dollar (SGD) Trading Against US Dollar – OCBC
LIVE QUOTES


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved