

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Higher oil prices fuel US Dollar demand, weakening Indian Rupee
- Strong US Dollar demand weighs on the Indian Rupee against the US currency.
- Easing concerns over a wider conflict within the Middle East pull oil prices lower.
- Traders expect RBI intervention near 95.30.
USD/INR edges up towards 95.22 in Tuesday’s opening trade. The Indian Rupee (INR) is again losing ground against the US Dollar (USD), with elevated oil prices sustaining substantial demand for the US currency.
At the time of writing, a 1.24% decline has taken the MCX Crude Oil contract expiring on 19 November to around Rs. 9,600. It nevertheless remains close to its recent highs of Rs. 9,828.
High oil prices typically weigh on the currencies of economies such as India, where imported oil meets a large share of energy needs.
Oil Pulls Back; Outlook Stays Firm
Reports that Iran, Saudi Arabia, Pakistan, and Turkey have agreed to pursue security discussions and strengthen regional cooperation have eased concerns about a wider Middle East conflict. Oil prices have consequently pulled back from recent highs.
According to a Monday report from the Islamic Republic of Iran Broadcasting (IRIB), senior-level talks in Tehran involving Saudi Arabia, Pakistan, and Turkey sought to represent the Mecca Joint Defence Agreement. The agreement said the four countries had committed to continued dialogue and consultations, notably on regional peace, security and stability.
However, a bullish outlook for oil continues to draw support from concerns that the United States (US) and Israel could restart attacks on Iran following their respective elections.
Political rhetoric from Washington is increasing the region’s exposure to higher energy costs, analysts at MUFG/BTMU warn. Pointing to US President Trump "hinting at renewed military action against Iran after the US midterm elections," they caution that any "renewed escalation that pushes crude materially higher would amplify the adverse terms-of-trade and inflation shock for the region’s net energy importers and those with current account deficits." Asian economies therefore remain particularly vulnerable to another oil price surge linked to Middle East risk.
95.30 in Focus as RBI Intervention Expected
After several days of uninterrupted depreciation in the Indian currency against the US Dollar, financial markets anticipate intervention soon from the Reserve Bank of India (RBI).
Traders cited by Reuters identify 95.30 as a crucial level, as the RBI has intervened more aggressively around it. They said a sustained break could leave the rupee vulnerable to a sharper fall towards 96 per dollar.
Wednesday’s Fed Decision Takes Centre Stage
The Federal Reserve’s (Fed) monetary policy announcement on Wednesday is set to be the principal catalyst for global markets this week.
Little event risk is expected in the formal communiqué accompanying the upcoming Fed decision, according to economists at Deutsche Bank. They note that “the statement itself [is] to contain only limited changes, although dissents to a hold are possible.” The economists add that “the interest will therefore be in Chair Warsh’s press conference and how the Fed balances still-elevated inflation and solid growth against the recent tightening in financial conditions,” with markets likely to examine his comments closely for any change in the policy narrative.
95.2405: USD/INR Technical Outlook
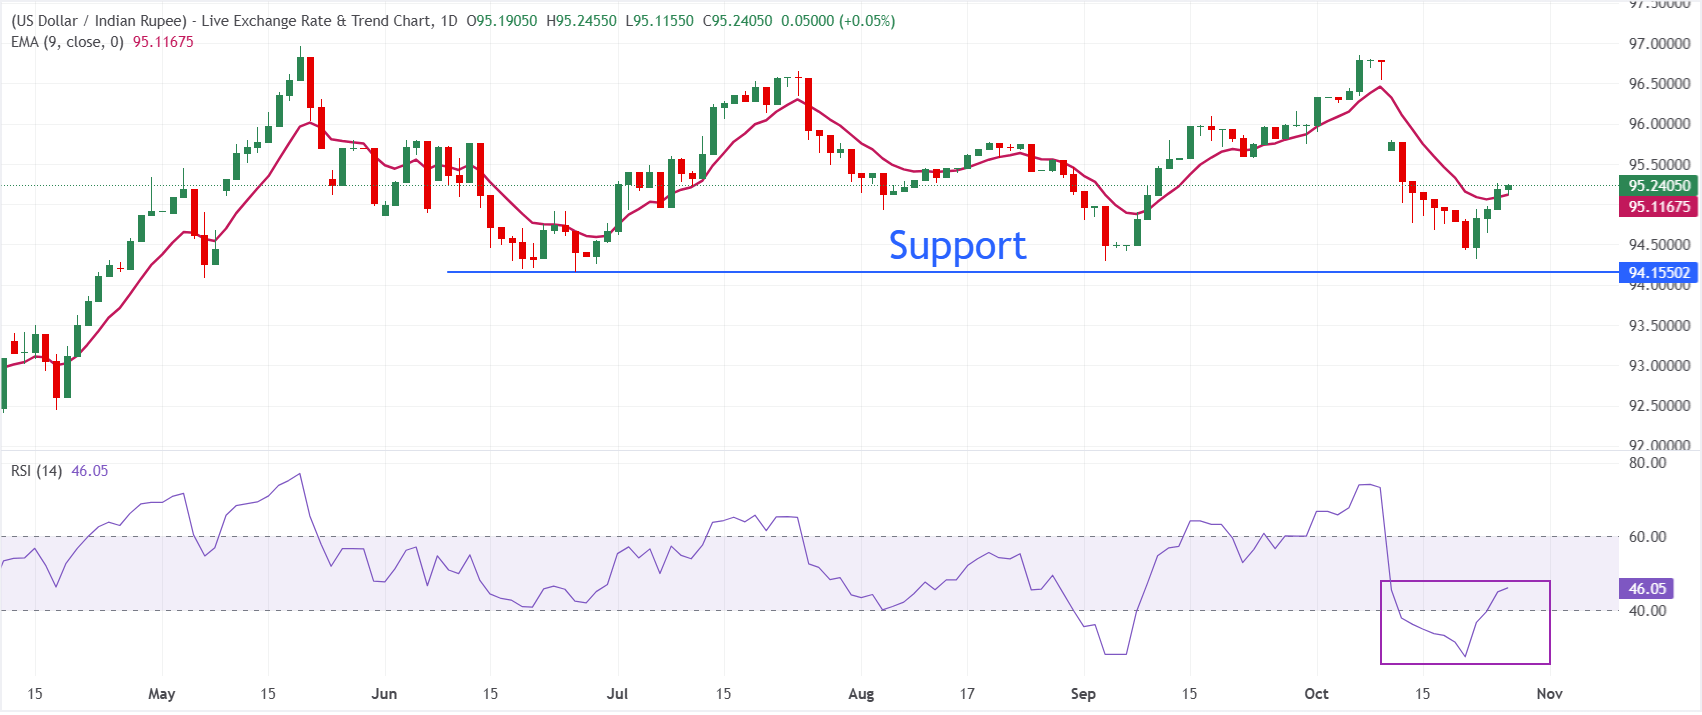
At 95.2405 on the daily chart, USD/INR remains marginally above its 9-period exponential moving average (EMA) of 95.1168, the immediate short-term support. Having pulled back from the mid-96s reached earlier this month, the pair shows signs of fading bullish momentum. The Relative Strength Index (RSI) stands at 46.05, below the 50 threshold, suggesting consolidation or a mild correction rather than a decisive directional move.
Traders will initially look to the 9-period EMA at 95.12 for downside support. A sustained breach would leave room for further declines towards the 25 June low of 94.16. Above the market, the 12 October high of 95.80 represents a key resistance level.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: Key Questions
External developments have a particularly strong influence on the Indian Rupee (INR). Major drivers include Crude Oil prices, given India’s heavy reliance on imported Oil, the US Dollar’s value, as most trade is settled in USD, and foreign investment levels. The Reserve Bank of India (RBI) also shapes the Rupee through direct FX market intervention to stabilise the exchange rate and through the interest rates it sets.
To support trade, the Reserve Bank of India (RBI) intervenes actively in foreign exchange markets to keep the exchange rate stable. It also adjusts interest rates in an effort to maintain inflation at its 4% target. Rate increases generally support the Rupee through the ‘carry trade’: investors borrow in lower-interest-rate countries and invest in countries offering relatively higher rates, earning the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and increase demand for the currency. A smaller trade deficit will ultimately strengthen the Rupee, while higher interest rates, particularly real rates after deducting inflation, are also supportive. Greater Foreign Direct and Indirect Investment (FDI and FII) inflows in a risk-on environment can provide further support.
Inflation generally weighs on the Rupee, especially when it exceeds that of India’s peers, because it signals devaluation caused by oversupply. By raising export costs, inflation also results in more Rupees being sold to pay for foreign imports, adding pressure on the currency. Conversely, higher inflation usually prompts the Reserve Bank of India (RBI) to raise interest rates. The resulting increase in international investor demand can support the Rupee. Lower inflation has the opposite effect.
POPULAR ARTICLES
1British Pound: Support from a calm budget backdrop and BoE outlook – Commerzbank2Indonesian Rupiah faces pressure as fiscal concerns, regional tensions and stronger USD cloud outlook3Euro: Support levels in focus amid downside bias against US Dollar – UOB4UK Budget approaches as British Pound advances against Japanese Yen5Dash Price Forecast: Bullish recovery gains traction as price stays above EMAs6Decisive FX market action: Japan’s Katayama says government stands ready7Higher oil prices fuel US Dollar demand, weakening Indian Rupee81.1150 area: EUR/USD eases as price forecast remains bearish below 100-day SMA9Above 0.7000: AUD/USD Holds as Bulls Await Break Above 100-SMA


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved