

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Will an expected acceleration in UK CPI pave the way for a BoE interest rate hike in November?
- Markets expect UK CPI inflation to reach its highest level since December last year, rising to 3.4% YoY in September from August’s 3.1%.
- As elevated energy costs feed through to the wider economy, core inflation is also expected to pick up.
- For the BoE, the readings could supply the decisive case for monetary tightening at its November meeting.
Expectations for the Bank of England’s next policy decision are in focus ahead of the September Consumer Price Index (CPI) release. The United Kingdom (UK) Office for National Statistics (ONS) is expected to publish the figures on Wednesday at 06:00 GMT, alongside the Producer Price Index (PPI) and Retail Sales report.
Investors are likely to scrutinise the consumer inflation readings for further clues to the Bank of England’s (BoE) forthcoming monetary policy decision. While Governor Andrew Bailey and some other BoE officials have highlighted the need for higher interest rates to contain inflationary pressure, they have offered little clarity on when the next move could come. UK inflation readings in line with market forecasts might reinforce expectations of a November rate increase, potentially lifting speculative demand for the British Pound (GBP).
Will the next UK inflation report show stronger price pressures?
Annual consumer inflation is forecast by the market consensus to climb from 3.1% in August to 3.4% in September. On a monthly basis, however, the expected increase of 0.3% would mark a slowdown from August’s 0.5% rise.
A more modest acceleration is anticipated in core inflation, which strips out volatile energy, food, alcohol and tobacco prices. Forecasts put September’s Core CPI at 2.8%, compared with 2.6% in August. That would provide further evidence that the energy shock arising from the Middle East conflict is feeding into the wider economy.
Since July, crude prices have climbed nearly 50%, including a gain of more than 10% so far in October. At the time of writing, Brent Oil is trading above $108.00 a barrel, a five-month high. With regional powers becoming increasingly entangled, a return to pre-war price levels appears unlikely anytime soon. This backdrop suggests inflationary pressure could remain elevated for an extended period, leaving central banks at risk of falling behind the curve unless they respond promptly.
Despite these conditions, the Bank of England remains among the few major central banks that have yet to tighten monetary policy in 2026. Calls for a rate increase have come from some BoE officials. At last week’s International Monetary Fund (IMF) summit in Bangkok, Governor Bailey voiced frustration over inflation remaining above target, strengthening investors’ confidence that some tightening will come before year-end.
The latest UK releases have lent support to that assessment. Tuesday’s ILO Unemployment Rate pointed to labour-market resilience, even as vacancies fell and the number of claimants increased more than expected. Monthly Gross Domestic Product (GDP) also delivered a positive surprise last week: August output expanded unexpectedly, supported by a strong industrial-sector performance. Taken together, these developments create favourable conditions for a quarter-point rate increase at next month’s meeting.
Could the UK Consumer Price Index report strengthen GBP/USD?
Among the major currencies, the British Pound ranks as one of this week’s strongest performers. Upbeat UK releases have improved confidence in the economic outlook while reducing worries about the cost of tax-relief measures pledged by Prime Minister Andy Burnham’s cabinet.
In their assessment of the latest economic releases, Commerzbank analysts say the data “gives the Bank of England room to raise rates without running the risk of putting additional pressure on an already weakening economy (...) Also takes some pressure off the Chancellor, who remains committed to reducing the budget deficit.”
In a note, Commerzbank adds: “How this can be achieved while at the same time providing relief to households and businesses facing high energy costs should become clearer when the budget is presented at the end of the month,”
With those worries receding for the time being, the Pound’s main support this week continues to come from robust UK figures and growing expectations that the BoE will finally raise rates in November. By comparison, the US Dollar remains weak as investors scale back wagers on consecutive Federal Reserve (Fed) rate increases. The Euro is also under pressure after protests in Paris turned violent, prompting the government to introduce curfews in several cities.
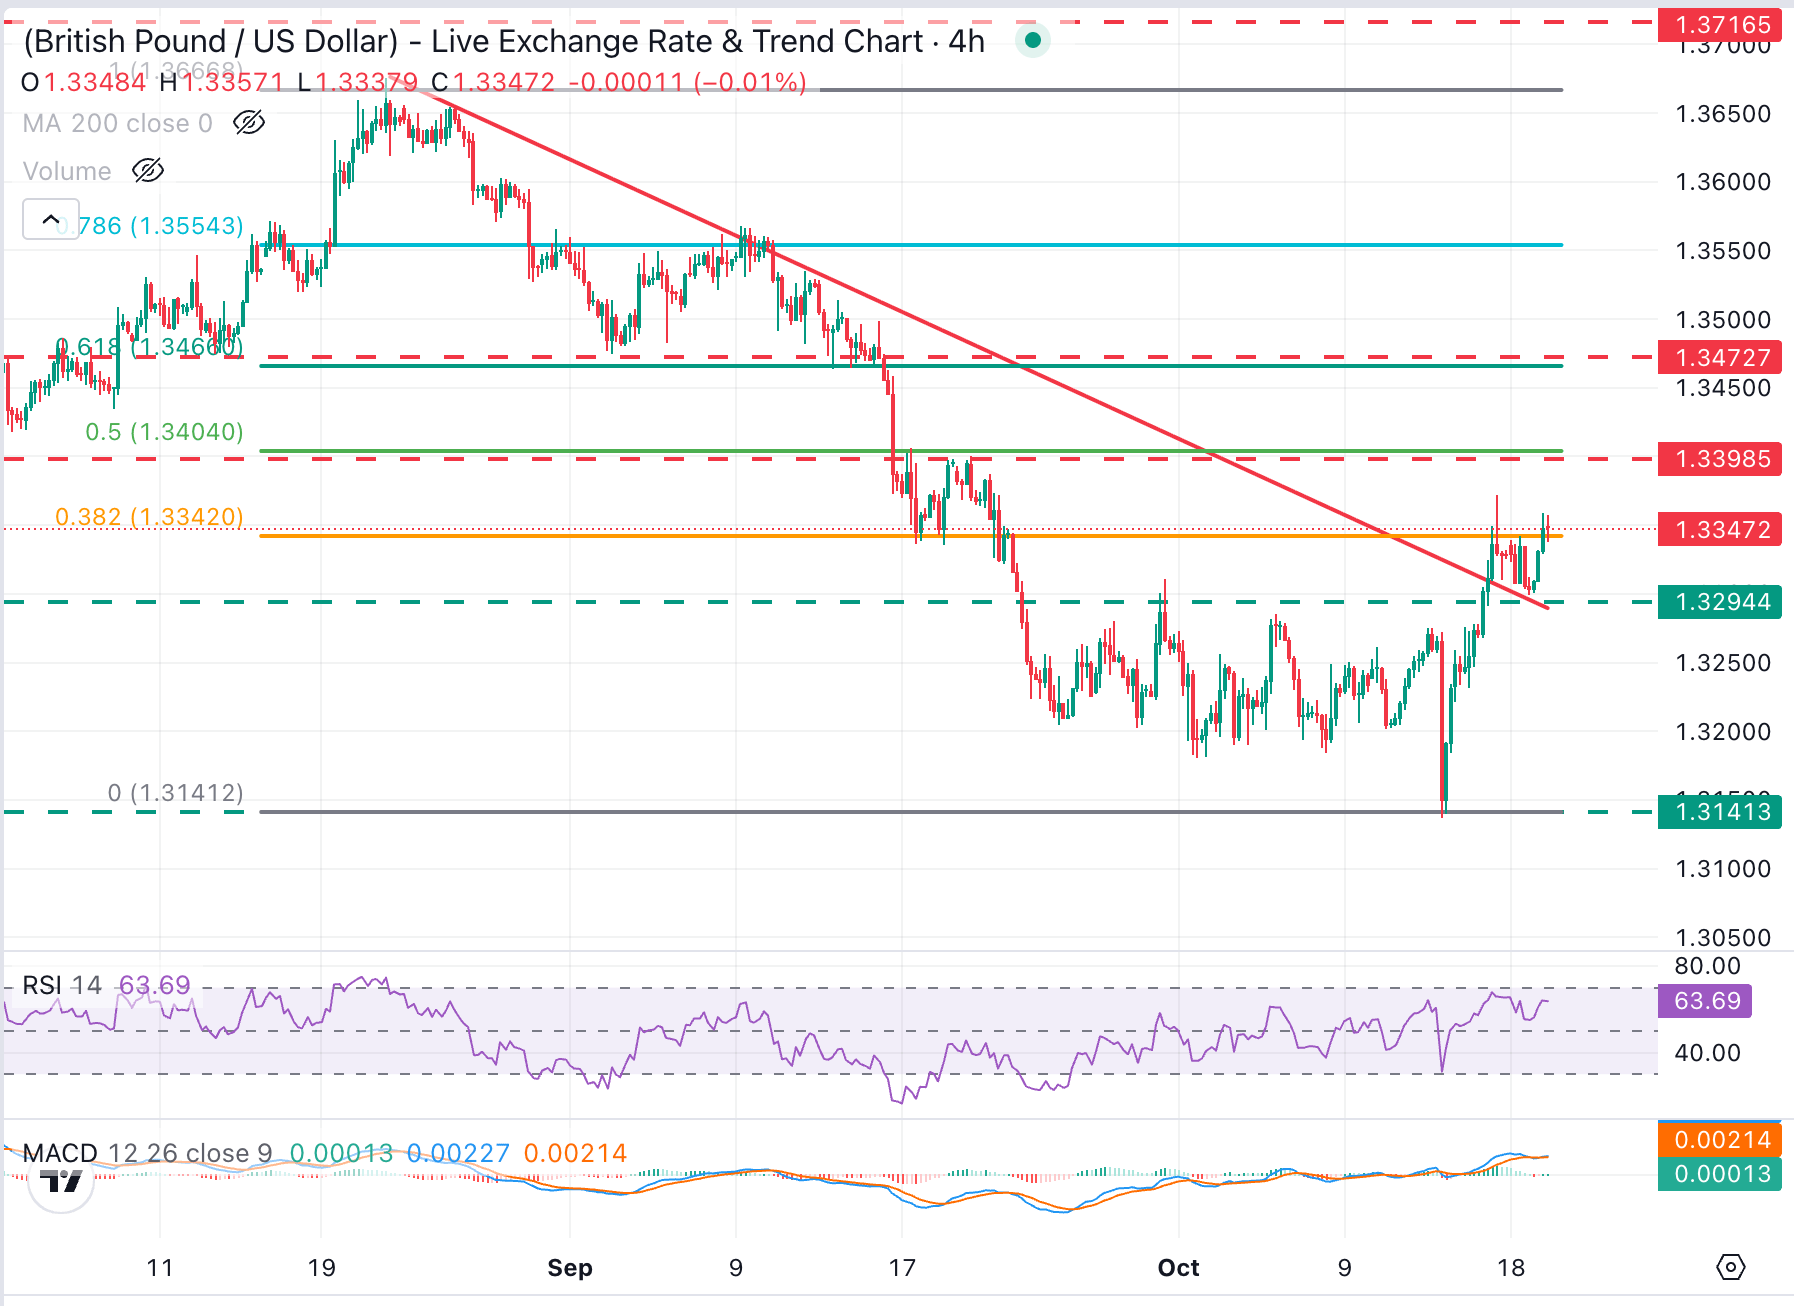
The near-term technical picture for GBP/USD is bullish on the 4-hour chart. A successful breakout above the descending resistance line drawn from the late August highs confirms that bias; the line was retested on Monday. Momentum signals offer support, with the Relative Strength Index (14) holding above 60. However, a Moving Average Convergence Divergence (MACD) reading that is virtually flat around zero indicates that the uptrend remains fragile.
The zone stretching from Friday’s 1.3370 high to the 22 September high near 1.3400 is likely to test buyers’ conviction. A confirmed move above these levels would shift attention to 1.3467, the 61.8% Fibonacci retracement of the August-October decline, followed by the former support area just above 1.3470, marked by the lows of 2 and 4 September.
For now, sellers are being held back by support around 1.3295, where the previously mentioned trendline meets the former range ceiling. A move back below this level would leave the year-to-date lows around 1.3140 exposed.
Common questions on interest rates
For borrowers, interest rates determine what financial institutions charge on loans; for savers and depositors, they determine the interest received. These rates respond to base lending rates, which central banks set as economic conditions change. Maintaining price stability is usually part of a central bank’s mandate and, in most cases, involves a core inflation target of around 2%. When inflation drops below target, a central bank may lower base lending rates to encourage lending and support economic activity. Conversely, inflation substantially above 2% usually prompts an increase in base lending rates aimed at bringing price growth down.
By making a country more attractive to international investors seeking somewhere to place their funds, higher interest rates generally support a stronger domestic currency.
Holding Gold carries a greater opportunity cost when interest rates rise, as investors could instead earn interest from other assets or bank deposits. Higher rates therefore tend to put downward pressure on Gold prices. High interest rates also usually strengthen the US Dollar (USD). Since Gold is priced in Dollars, a stronger Dollar has the effect of reducing its price.
US banks lend to one another overnight at the Fed funds rate. This widely cited headline rate is set by the Federal Reserve at its FOMC meetings and is expressed as a range, such as 4.75%-5.00%. The figure usually quoted is the upper end of that range, which in this example is 5.00%. The CME FedWatch tool tracks market expectations for the future Fed funds rate. Those expectations influence behaviour across many financial markets ahead of forthcoming Federal Reserve monetary policy decisions.
Economic data indicator
Core Consumer Price Index: annual change (YoY)
Published monthly by the Office for National Statistics, the United Kingdom (UK) Core Consumer Price Index (CPI) measures consumer price inflation to international standards. Consumer price inflation describes the rate at which prices rise or fall for goods and services purchased by households. Its YoY reading compares prices in the reference month with those a year earlier, while the core measure leaves out volatile food, energy, alcohol and tobacco components. Core CPI is an important gauge of inflation and shifts in purchasing trends. A higher reading is generally regarded as supportive of the Pound Sterling (GBP), whereas a lower reading is generally viewed as negative for the currency.
Read further.Next scheduled release: Wed 21 Oct 2026 06:00
Publication frequency: Every month
Consensus forecast: 2.8%
Previous reading: 2.6%
Data source: Office for National Statistics
A stronger-than-expected inflation reading generally supports GBP. The monthly release is significant because the Bank of England has a mandate to keep inflation, measured by the headline Consumer Price Index (CPI), at around 2%. Rising inflation points to earlier and faster interest rate increases or a reduction in bond purchases by the BOE, tightening the supply of pounds. By contrast, a slowdown in price increases signals looser monetary policy.
POPULAR ARTICLES
1New Zealand Dollar slips below 0.5700 amid RBNZ rate hike bets; attention turns to CPI inflation data2Ethereum staking reaches a record high as yield and fee revenue decline3Can the Japanese Yen withstand Japan’s widening Trade Deficit and the BoJ’s cautious stance?4Will an expected acceleration in UK CPI pave the way for a BoE interest rate hike in November?5Can the British Pound Recover as It Slips Below 1.3400 Ahead of UK CPI Inflation Data?6Hawkish RBA counters USD gains, keeping Australian Dollar near monthly high above 0.70007Can WTI Sustain Gains Above $98.50 Amid Middle East Supply Risks?8PBOC’s USD/CNY reference rate moves to 6.7192 from the previous 6.72009French protests and fiscal risks weigh on euro as it slips below 1.1250
LIVE QUOTES

ALL ABOUT FOREX
Margin Call Meaning: What It Is, What Triggers It, and How to Avoid One
What Is an Islamic Account in Forex?
Best Indicators for Forex Trading and How to Use Them
The Top 10 Most Traded Currency Pairs in the World
What are the Major Forex Pairs? 7 Major Currency Pairs in the World
5 Best Forex Trading Apps In India In 2026
Top 15 Weakest Currencies in the World
Best Time to Trade Forex
Forex Trading Regulations in India
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved