

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
What lies ahead for a flat Yen with Tokyo inflation and a BoJ rate decision next?
- Disappointing Amazon and Intel results weigh on USD/JPY, leaving it just above 157.50.
- A December Fed rate increase is already priced into futures despite stronger-than-forecast US growth.
- Ahead of Friday's BoJ decision, most analysts anticipate a December rate increase.
The Dollar remains weaker against the Yen following disappointing results from Amazon (AMZN) and Intel (INTC), despite US growth exceeding forecasts. Around the European Central Bank's (ECB) decision, USD/JPY touched a session peak just above 158.00. Two retreats from that level have since left the pair just above 157.50, close to the lower end of its trading range for the session.
Neither the growth figures nor the inflation reading prompted much movement in USD/JPY. Third-quarter US growth came in at an annualised 3.4%, exceeding the 3.2% forecast, while core Personal Consumption Expenditures Price Index (PCE) inflation was in line with expectations at 3.1%. Following Wednesday's 10-2 vote to leave rates unchanged, futures put the probability of a December Fed increase at nearly 85%. Such a move would take the US interest rate underpinning USD/JPY's rate differential to 4.00%-4.25%.
With its policy rate at 1.25%, the Bank of Japan (BoJ) opened a two-day meeting on Thursday. A Reuters poll shows that most analysts anticipate a rate of 1.5% in December. September saw quarter-point increases by both the Fed and the BoJ, leaving the rate differential for USD/JPY unchanged at 2.50-2.75 points.
Which releases and speeches are due?
The timing of the BoJ's next rate increase will be in focus across the upcoming releases and appearances. Tokyo's October Consumer Price Index (CPI) is scheduled for Thursday at 23:30 GMT, with prices excluding fresh food expected to rise 2.6%, following 2.7%. Friday brings the BoJ decision, with no fixed release time, followed by BoJ Governor Ueda's news conference at 06:30 GMT. Ueda is also due to speak at 16:00 GMT on 6 November.
Friday's speaking schedule includes San Francisco Fed President Daly at 16:00 GMT and St. Louis Fed President Musalem at 16:30 GMT. The October Nonfarm Payrolls (NFP) report, due at 13:30 GMT on 6 November, will inform the Fed's December decision. It follows September's increase of 29K.
What do the charts indicate?
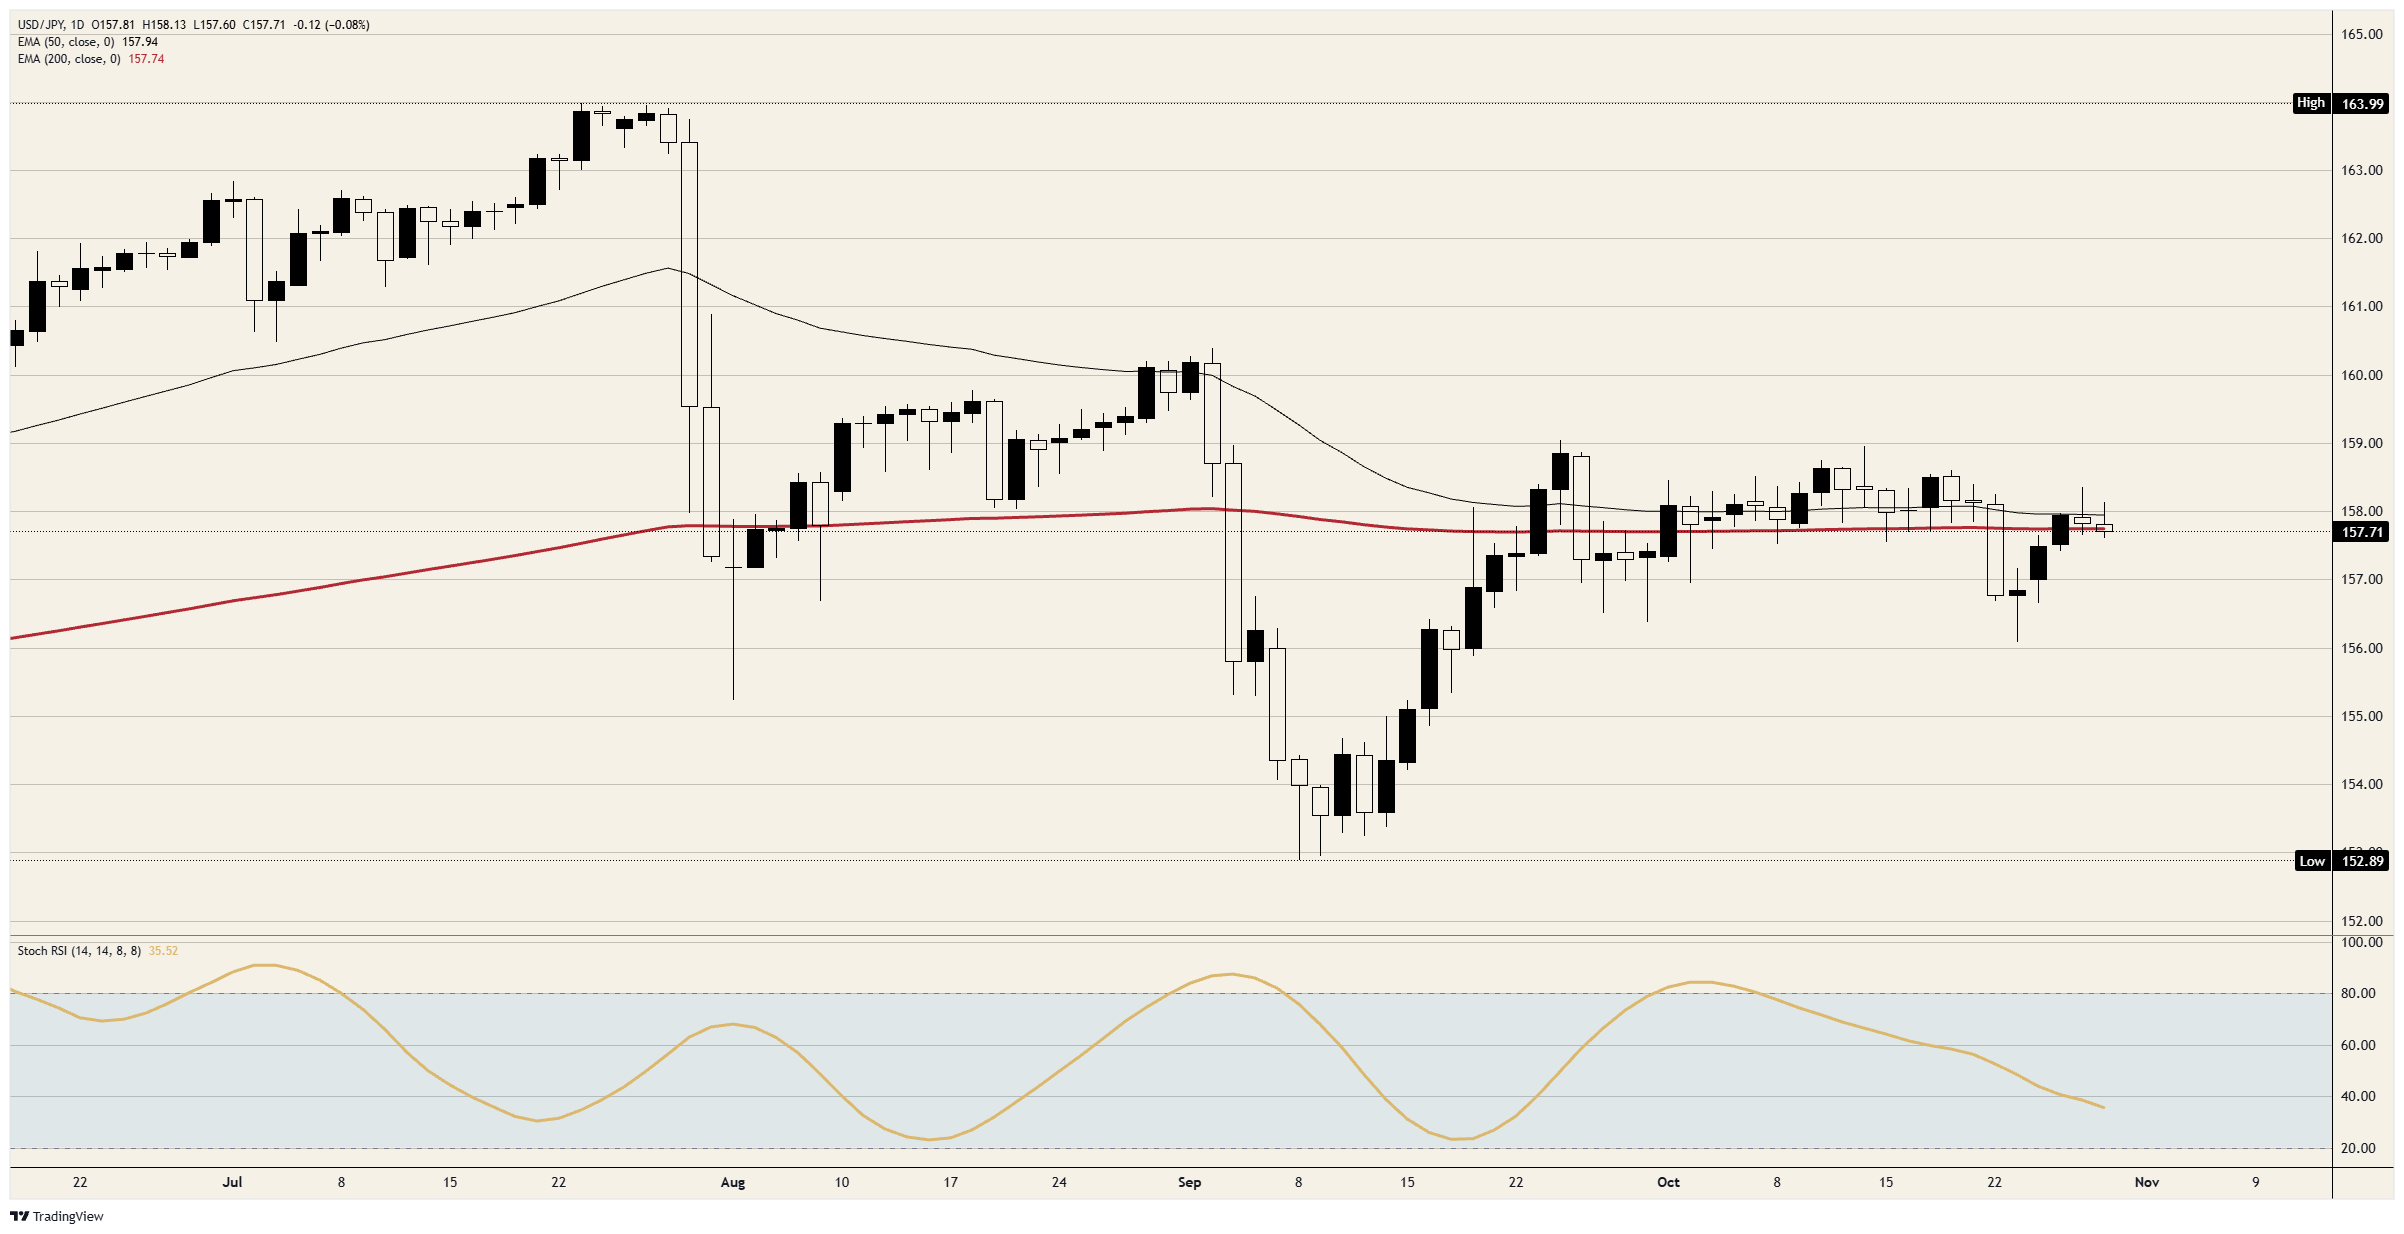
At current levels, USD/JPY sits on its 200-day Exponential Moving Average (EMA), while the 50-day average is marginally above it. The rebound from an early-September trough just below 153.00 stalled just above 159.00 on 24 September; that peak has not been surpassed since. So far, the pair has retraced slightly more than two-fifths of the decline from its late-July peak just below 164.00.
Daily chart for USD/JPY
Common questions about the Japanese Yen
Among the most actively traded currencies globally, the Japanese Yen (JPY) takes its broad direction from Japan's economic performance. More specific influences include the Bank of Japan's monetary policy, the gap between Japanese and US bond yields, and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions important for the Yen. At times, the BoJ has intervened directly in foreign exchange markets, usually to weaken the currency. However, political concerns among Japan's main trading partners have discouraged frequent intervention. Between 2013 and 2024, an ultra-loose monetary stance weakened the Yen against its major peers as the policy gap between the Bank of Japan and other leading central banks grew. More recently, a gradual withdrawal of that ultra-loose policy has offered the Yen some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ increasingly diverged from other central banks, notably the US Federal Reserve. The resulting widening of the yield gap between 10-year US and Japanese bonds supported the US Dollar relative to the Japanese Yen. That differential is now narrowing as other major central banks cut interest rates and the BoJ follows its 2024 decision to move gradually away from ultra-loose policy.
Investors often regard the Japanese Yen as a safe-haven asset, turning more readily to it during periods of market stress because of its perceived stability and reliability. As a result, turbulent conditions are likely to lift the Yen against currencies considered riskier investments.
POPULAR ARTICLES
1What lies ahead for a flat Yen with Tokyo inflation and a BoJ rate decision next?2GBP/JPY Price Forecast: Can bulls reach 213.00 after retaking the 50-day SMA?3Ethereum Price Forecast: Why is ETH slipping as US PCE inflation strengthens the case for a December rate hike?4Thai Baht: Does the double-top point to a potential reversal against the US Dollar? – OCBC5Bank of Japan set to keep interest rates unchanged at 1.25%6South Korean Won: Stronger equities offer no lift to KRW against US Dollar – OCBC7Breaking: Has Binance been hacked for $2.77 billion?8Why Is the Mexican Peso Falling as US Growth and Hot Inflation Revive Fed Rate Hike Bets?9Thai Baht: What Are the Curve-Steepening Risks as BoT Holds Rates? – DBS


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved