

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
How will the Euro respond to PMIs first and France’s credit rating over the weekend?
- Why is EUR/USD stalled below 1.1250 as France's 10-year yield crosses 5%?
- October's four rallies have produced successively lower peaks.
- Friday brings Moody's assessment of France's credit rating.
EUR/USD remains just below 1.1250, with the Euro barely reacting as France's 10-year government bond yield crossed 5% on Wednesday for the first time since 2002. All four advances since 2 October have peaked below the preceding rally. France's yield spread is weighing on the currency, while the interest rate differential with the US offers no offset: both the Fed and the European Central Bank (ECB) are expected to leave rates unchanged in October before raising them in December.
Why is France paying 1.6 points more than Germany for 10-year borrowing?
At about 1.6 points, the spread between French and German 10-year yields reached its widest since 2012. France's yield briefly exceeded 5% before easing below that mark, while Germany's stood near 3.4%. Meanwhile, five-year insurance against French debt default is at its most expensive since 2013. Government debt amounts to nearly 120% of the economy. After more than 2K amendments delayed proceedings, parliament will resume debating the 2027 budget on 27 October.
Pressure from a widening French spread extends to the Euro as a whole: it increases the possibility of the ECB having to prioritise either its inflation target or a member state's bond market. Created in 2022 to address that dilemma, the ECB's Transmission Protection Instrument (TPI) remains unused. On 14 October, ECB President Lagarde said France needed to find the solution domestically through its own fiscal policy.
Political developments also account for part of the spread. Partial curfews have been imposed in Paris, Bordeaux and Nice following student protests. Troops are scheduled to assist police during Saturday's planned marches, a day after Moody's assessment of France's rating.
Can the EUR/USD rate differential shift before December?
Traders assign roughly a 95% probability to an ECB pause on 29 October, following increases in June and September that took the deposit rate to 2.50%. September inflation in the euro area stood at 3.8%, including an 18.9% year-on-year rise in energy prices. Excluding energy, food, alcohol and tobacco, inflation was 2.5%. Higher interest rates do little to address energy costs driven by the US-Iran war.
With energy inflation remaining elevated, ECB Chief Economist Lane urged caution over further policy moves on Wednesday. Bundesbank President Nagel, however, said on 16 October that another increase could not be ruled out. Across the Atlantic, the Fed's rate range stands at 3.75%-4.00%, with prediction markets assigning close to an 86% probability to unchanged rates on 28 October. Expectations of October pauses and December moves at both central banks leave little scope for the US-euro area rate differential to change before then. Chief Economist Lane also suggested that broader use of the Euro beyond Europe could aid the ECB's efforts to control prices, even as the currency's greatest risk that day originated within the region.
What do Friday's PMIs and Moody's review mean ahead of the weekend?
Thursday's schedule includes remarks from Bank of Italy Governor Panetta at 12:15 GMT, followed at 14:00 GMT by preliminary euro area consumer confidence, forecast at -17 versus -16.5 previously. On Friday at 08:00 GMT, Hamburg Commercial Bank (HCOB) Purchasing Managers Index (PMI) readings are expected at 52.8 for manufacturing, down from 52.9, and 52.8 for services, against 53.0 previously. Remarks from ECB Executive Board member Cipollone are due at 14:00 GMT.
S&P Global's US PMIs are due next at 13:45 GMT on Friday. Forecasts of 55.6 for manufacturing and 57.9 for services exceed all the expected euro area readings. Despite the Dollar Index easing to just below 102.00 from October's 18-month peak near 103.00, EUR/USD has drawn little support from Dollar weakness. Moody's assessment of France also falls on Friday. Under EU rules, agencies must release sovereign rating decisions after European markets close, meaning EUR/USD will trade the PMI figures before the rating is available and reopen on Monday with the decision known.
Which Euro levels matter as successive highs decline?
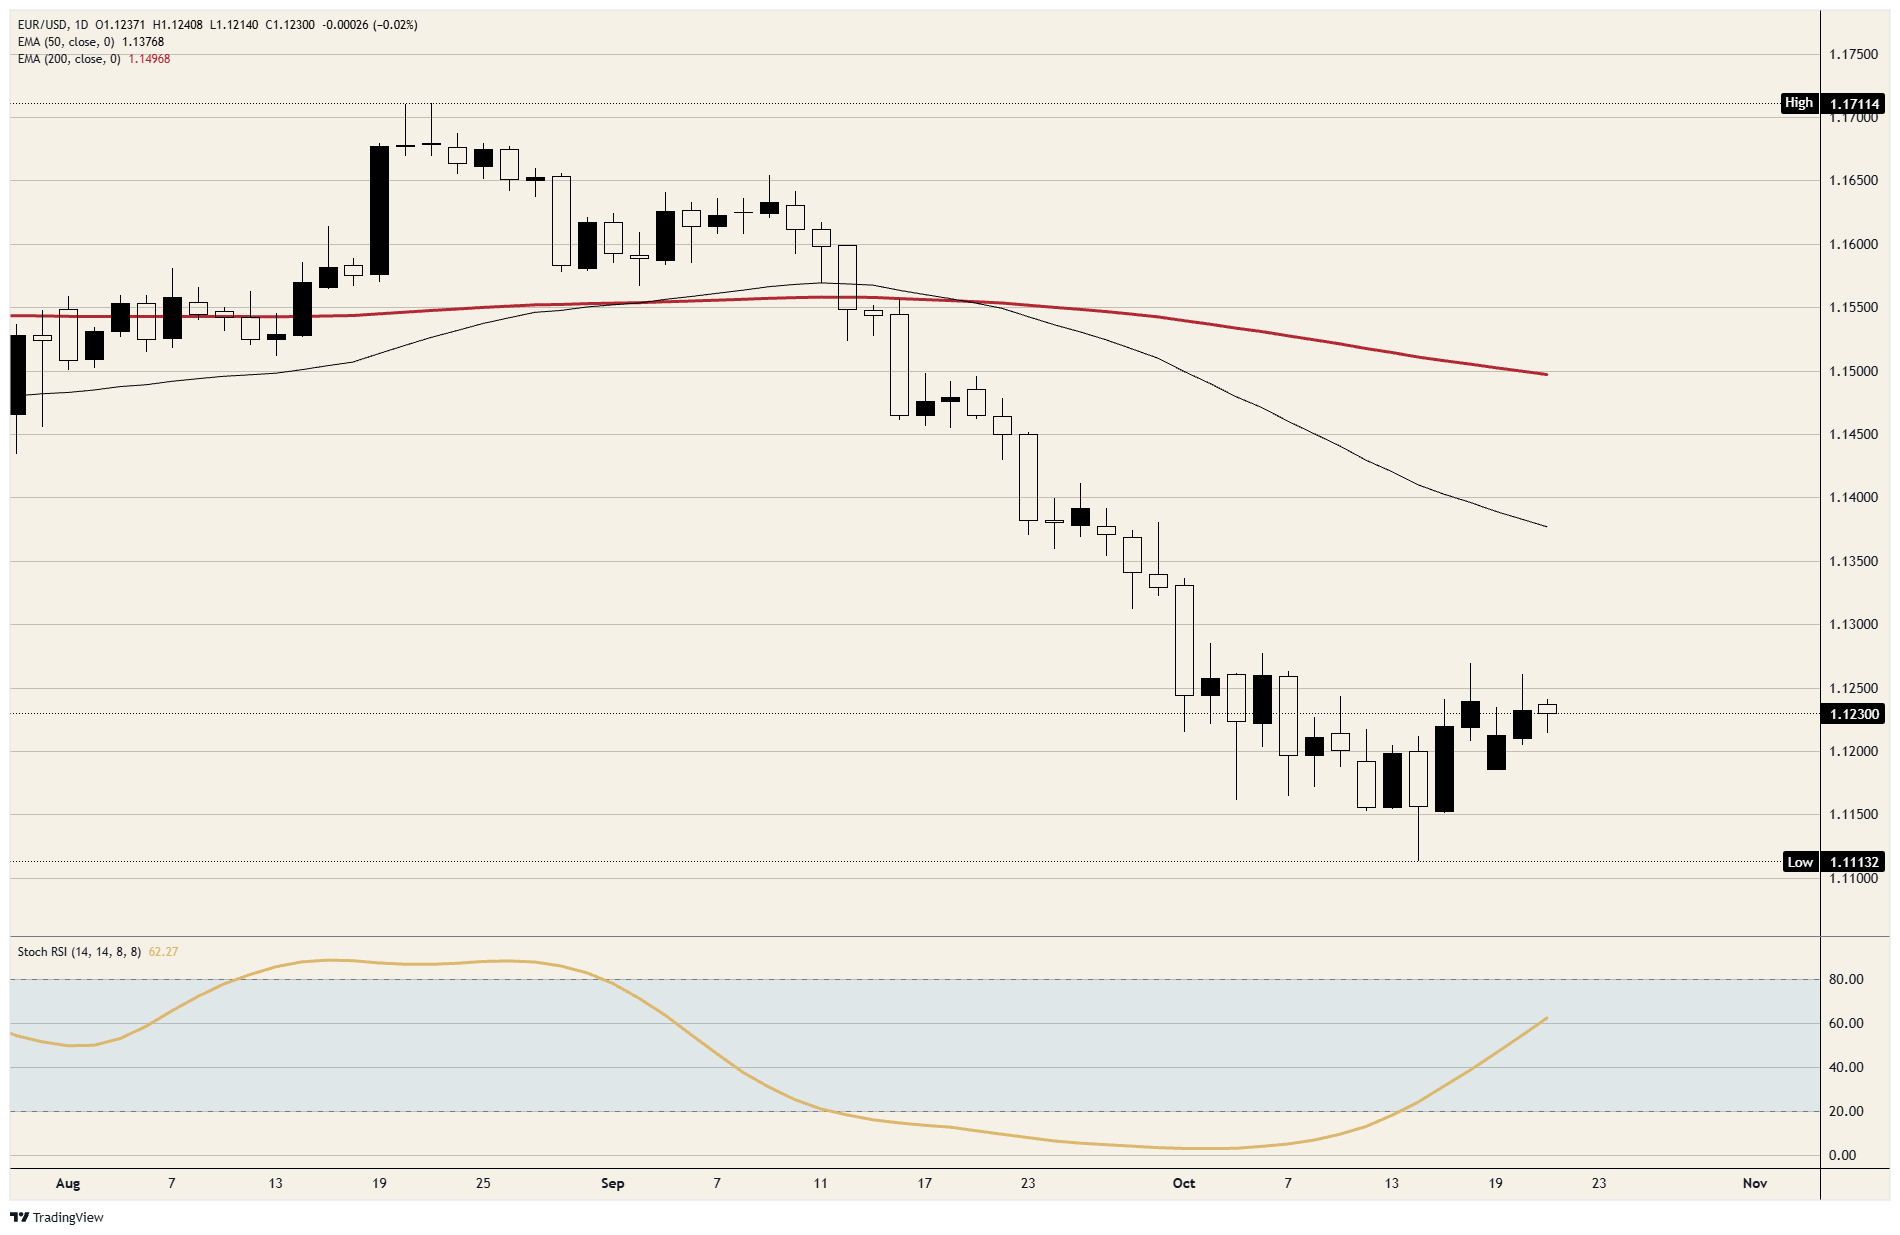
Resistance: Wednesday's advance was capped at 1.1250, after Tuesday's peak had only marginally exceeded that level. Successive October highs have fallen from just below 1.1300 on 2 October, and the last time EUR/USD traded above 1.1300 was 1 October.
Support: Following Monday's brief dip below 1.1200, that level has held. The pair found a floor at 1.1150 on both 12 October and 15 October. The range's lower boundary is the 14 October low, just above 1.1100.
Bias: A close below 1.1250 favours a short stance, with 1.1150 as the first target and 1.1100 thereafter. Since mid-October, the daily Stochastic Relative Strength Index (Stoch RSI) has risen from near zero to around 62 and continues to climb. That momentum could interrupt the sequence of lower highs. A daily close above 1.1300 invalidates the short position.
Daily EUR/USD chart
Euro: common questions
Only the US Dollar is traded more actively worldwide than the Euro, the shared currency of the 20 European Union countries within the Eurozone. The Euro represented 31% of all foreign exchange transactions in 2022, with daily turnover averaging more than $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world's most actively traded currency pair. EUR/JPY follows at 4%, ahead of EUR/GBP at 3% and EUR/AUD at 2%.
Interest rates and monetary policy for the Eurozone are managed by the European Central Bank (ECB), the region's central bank, based in Frankfurt, Germany. Maintaining price stability is the ECB's main mandate, requiring it either to curb inflation or support growth. Adjusting interest rates upwards or downwards is its principal policy tool. The Euro generally benefits when rates are relatively high or expected to rise; the reverse also applies. Monetary policy is decided at the ECB Governing Council's eight meetings each year. Decision-makers comprise the heads of the Eurozone's national central banks and six permanent members, among them ECB President Christine Lagarde.
The Euro is sensitive to Eurozone inflation readings compiled through the Harmonised Index of Consumer Prices (HICP), a key economic measure for the currency. A stronger-than-expected rise in inflation, particularly beyond the ECB's 2% target, requires the central bank to increase interest rates to regain control over prices. When the region's interest rates are relatively high compared with those elsewhere, global investors find it more attractive to place funds there. This generally supports the Euro.
The Euro can react to economic releases because they reveal the economy's underlying health. GDP, manufacturing and services PMIs, employment figures and consumer sentiment surveys can each shape the single currency's direction. Economic strength supports the Euro by drawing in additional foreign investment and potentially prompting the ECB to raise interest rates, which directly strengthens the currency. Weak economic readings, by contrast, are likely to weigh on the Euro. Germany, France, Italy and Spain together represent 75% of the Eurozone economy. Figures from these four largest euro area economies therefore carry particular significance.
The Trade Balance is another release that matters for the Euro. Over a specified period, it compares a country's export earnings with its spending on imports. Strong overseas demand for a country's exports creates additional demand for its currency as foreign buyers seek to purchase those products, lifting the currency's value. A positive net Trade Balance consequently supports a currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1Why is the Japanese Yen barely moving as a Bank of Japan deputy flags inflation risk?2AUD/JPY Price Forecast: Can a Double Bottom Help Bulls Reach 113.50?3Chinese Yuan: Can gradual gains against US Dollar extend towards 6.6640? – UOB4GBP/JPY Price Forecast: Can bulls withstand the Doji challenge below 212.00?5How will the Euro respond to PMIs first and France’s credit rating over the weekend?6Why is the Australian Dollar shrugging off Iran war jitters as RBA hike bets double?7British Pound heads towards retail sales release with November rate hike already factored in8Below the 3.8% forecast: New Zealand’s Q3 CPI inflation slows to 3.7% YoY9Indonesian Rupiah: Bias towards depreciation amid MSCI risk – MUFG
LIVE QUOTES


ALL ABOUT FOREX
Margin Call Meaning: What It Is, What Triggers It, and How to Avoid One
What Is an Islamic Account in Forex?
Best Indicators for Forex Trading and How to Use Them
The Top 10 Most Traded Currency Pairs in the World
What are the Major Forex Pairs? 7 Major Currency Pairs in the World
5 Best Forex Trading Apps In India In 2026
Top 15 Weakest Currencies in the World
Best Time to Trade Forex
Forex Trading Regulations in India
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved