

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Crude Oil sees little change after Fed hold as Iran considers a Qatari deal
- WTI holds near $102.00 after rising from below $100.00, with little reaction to the Fed's decision to keep rates unchanged.
- US Crude Oil inventories declined by 1.9 million barrels, while gasoline stocks increased by 3.9 million.
- A response from Iran to Qatar's draft agreement to end the war is expected by Friday.
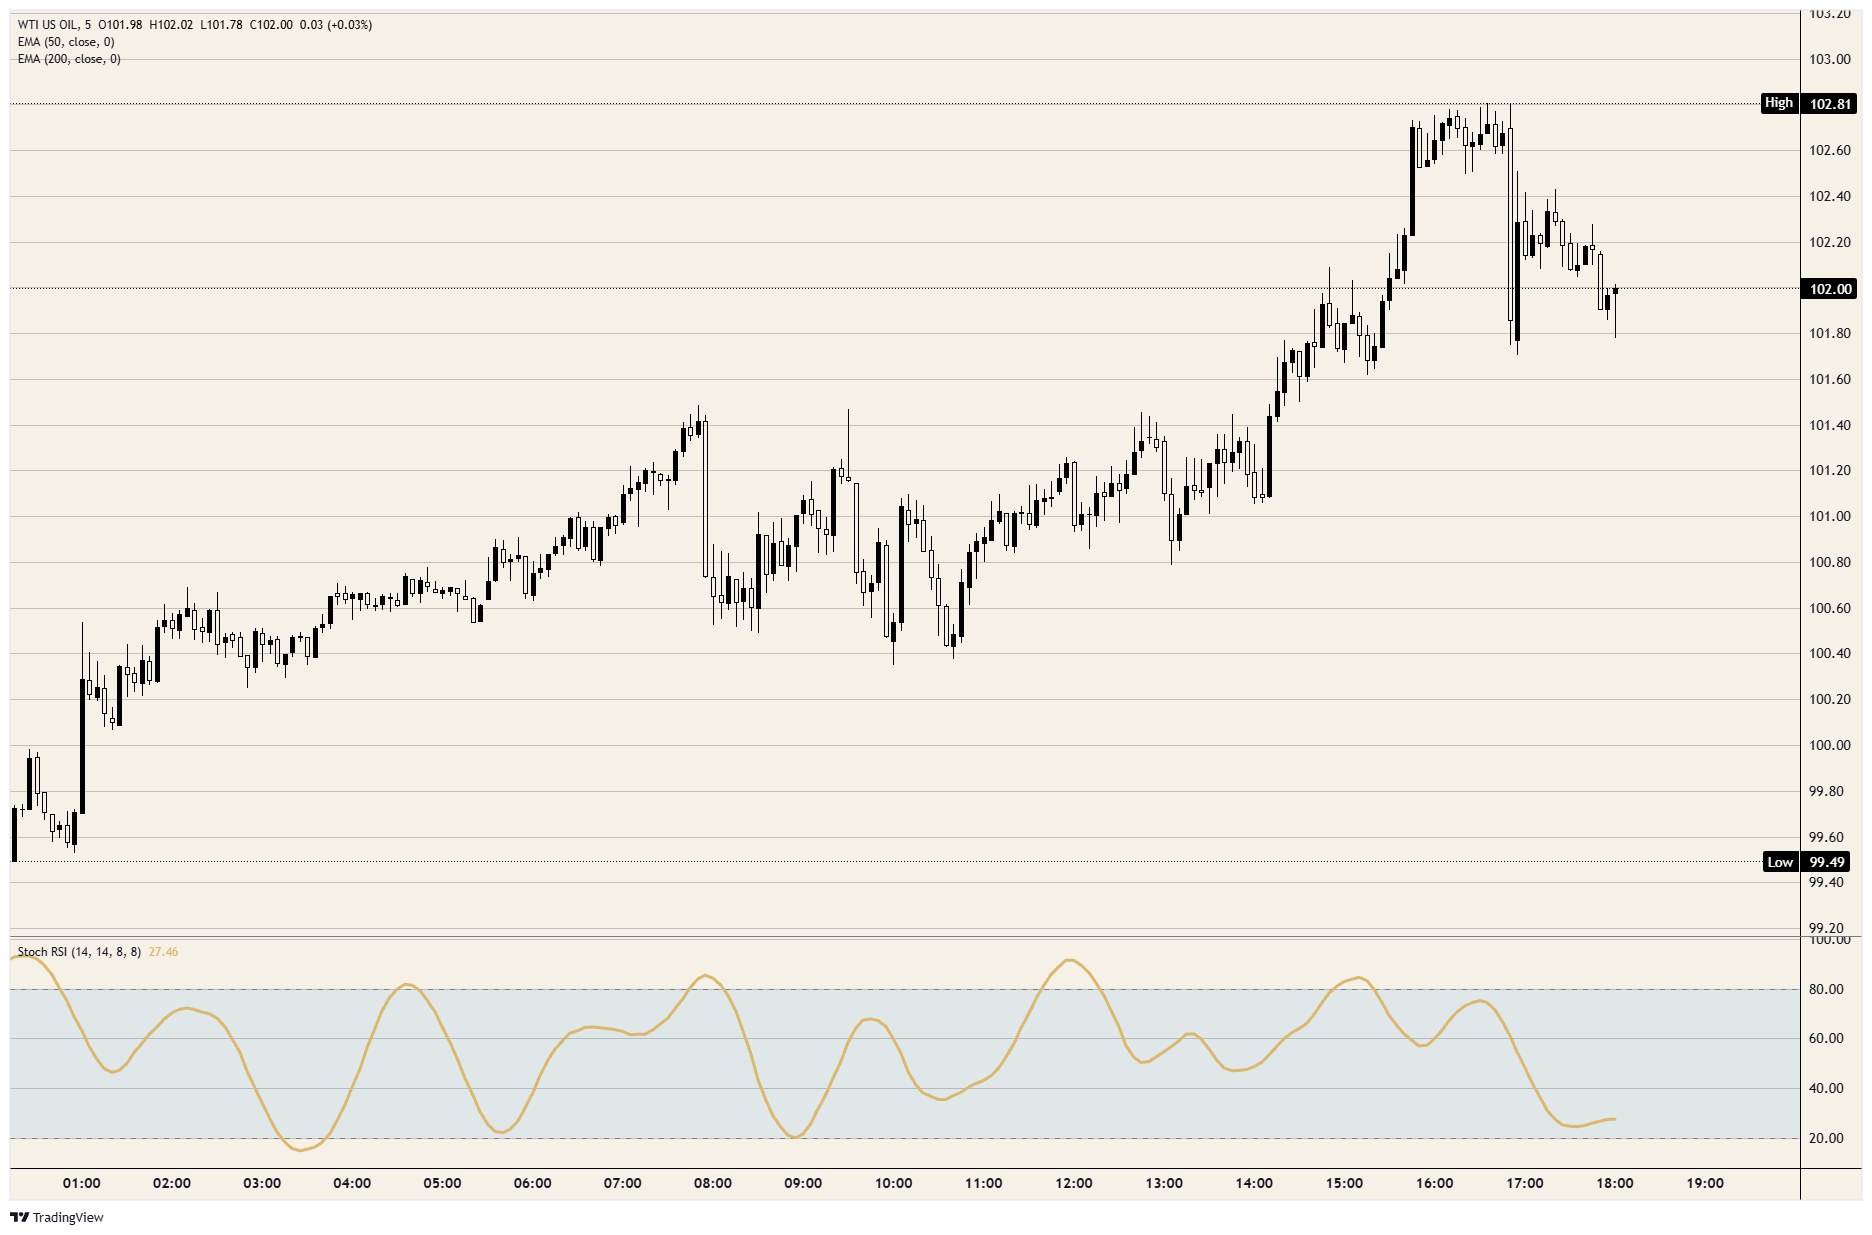
WTI showed little reaction to the Fed statement, trading around $102.00 and below its pre-decision session peak of just under $103.00. For Crude Oil, Qatar's draft agreement to end the war carries more weight than the Fed's decision to leave rates unchanged. Iran is expected to respond to the proposal before the weekend.
After Qatari mediators handed Iran the draft, an official told Reuters on Wednesday that Tehran was considering the proposal. Separately, The Wall Street Journal reported that Washington had asked Gulf states to prepare for a possible resumption of the US campaign against Iran after the November 3 midterms. Both scenarios would alter the volume of Gulf Crude Oil available to buyers, influencing the supply backdrop against which WTI is priced.
US Crude Oil inventories, which underpin WTI, declined by 1.9 million barrels in the week to October 23, according to the Energy Information Administration (EIA). Gasoline inventories, by contrast, increased by 3.9 million barrels. A 5.2% decline in global supply in 2026 is expected by the World Bank, marking the largest fall in over four decades apart from 2020. Also on Wednesday, Abu Dhabi National Oil Company (ADNOC) informed customers that its pipeline bypassing the Strait of Hormuz would start operating in early 2027.
What is next on the calendar?
With no specific day confirmed, Tehran is expected to respond to Qatar's draft before the weekend. The key indicator this week of the US demand underpinning WTI will be Thursday's advance estimate of third-quarter US Gross Domestic Product (GDP), due at 12:30 GMT.
At 18:30 GMT on Wednesday, Fed Chair Warsh's press conference will mark his first public remarks since Fed officials entered their quiet period on October 17. A day before that period began, he described inflation as uncomfortably high. His assessment of whether energy costs are feeding into other prices will have implications for a December rate hike, which would weigh on that same US demand.
What do the charts indicate?
After opening Wednesday just below $100.00, WTI advanced through most of the session. The bars following the EIA release showed one of its larger upward moves. Before the Fed decision, however, a single five-minute bar erased more than half of the gains made since that report. Intraday momentum has moved higher from close to oversold territory.
WTI spot: 5-minute chart
Interest rates: frequently asked questions
For borrowers, interest rates determine the charges financial institutions levy on loans; for savers and depositors, they determine the interest paid on their money. These rates are influenced by base lending rates, which central banks adjust in response to economic developments. Ensuring price stability is normally part of a central bank's mandate, usually through a core inflation target of around 2%. When inflation drops below target, a central bank may lower base lending rates to encourage lending and support economic activity. Conversely, inflation substantially above 2% normally prompts an increase in base lending rates to bring price pressures down.
By making a country more attractive to global investors looking to place their funds, higher interest rates generally support its currency.
Holding Gold rather than an interest-bearing asset or a bank deposit carries a higher opportunity cost when interest rates rise. Higher rates therefore generally put pressure on Gold prices. High interest rates also usually strengthen the US Dollar (USD). As Gold is priced in Dollars, this tends to push its price lower.
US banks lend to one another overnight at the Fed funds rate. Set by the Federal Reserve at its FOMC meetings, this is the headline rate commonly cited in reports. Although it is expressed as a range, such as 4.75%-5.00%, the figure usually quoted is the upper bound, in this example 5.00%. The CME FedWatch tool tracks market expectations for the future Fed funds rate. These expectations influence behaviour across many financial markets ahead of Federal Reserve monetary policy decisions.
POPULAR ARTICLES
1British Pound regains ground as Fed keeps rates unchanged amid hawkish divisions2Crude Oil sees little change after Fed hold as Iran considers a Qatari deal3Canadian Dollar Sees Little Change as Fed Holds Rates After BoC Hike4Euro ticks higher as Fed stands pat, with ECB a day away5Dollar Index recovers from a dip as Fed holds rates, with two votes for a hike6WTI ends two-day run of losses as fresh developments unfold in the Middle East7Silver Price Forecast: Is $50 Back in Focus After Rejection at $55?8Why is gold slipping towards $4,000 as oil above $100 clouds the Fed’s rate outlook?9Ahead of Fed decision, New Zealand Dollar slides sharply as RBNZ keeps rates on hold
LIVE QUOTES


ALL ABOUT OIL
5 Best Oil Trading Platforms 2026 (Brent and WTI)
Iran War and the Global Economy in 2026: Oil, Inflation, Trade and Markets
Should You Still Invest in Oil in 2026?
WTI vs Brent Crude
Gold to Oil Ratio: How does the Iran War affect Gold Prices?
Top 10 Most Traded Commodities in India & The Best Commodity to Trade
What is WTI Oil: Importance, Purpose, How To Trade
Trading Brent Crude Oil: A Comprehensive Guide
How to Trade Oil in India: Steps, Markets and Risks
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved