
News & AnalysisCareer

October’s preliminary United States (US) S&P Global Purchasing Managers Indices (PMIs), due on Friday, will offer a fresh assessment of the world’s largest economy before the Federal Reserve (Fed) holds its monetary policy meeting next week.
Private-sector business activity is assessed through the report’s Manufacturing PMI, Services PMI and Composite PMI. A reading above 50 denotes expansion; below that level, it indicates contraction.
Recent US data have continued to show resilient economic activity despite sustained inflationary pressures and high borrowing costs, setting the backdrop for October’s surveys. Investors will scrutinise the results for evidence of weaker growth and renewed price pressures, either of which could shape the Fed’s policy outlook and the US Dollar (USD).
Following September’s notably strong results, markets anticipate a modest loss of momentum in US private-sector activity in October. The S&P Global Manufacturing PMI is forecast to edge down from September’s 55.9 to 55.6, while the Services PMI is expected to fall from 58.8 to 57.9. September’s Composite PMI reading of 58.4, meanwhile, pointed to vigorous growth across the US private sector.
Even with some moderation expected in both sectors, forecasts remain well above the 50 mark. The anticipated readings therefore suggest that the US economy is still growing at a healthy rate.
Persistent inflationary pressures lend particular significance to this release. Inflation has exceeded expectations in recent US data, while Retail Sales and labour market measures continue to point to resilient domestic demand.
Following September’s 25-basis-point (bps) increase, the Fed is widely expected to hold interest rates steady at its 28 October meeting. The CME FedWatch tool nevertheless shows that investors have fully priced in a further rate rise in December.
Friday at 13:45 GMT will bring the October S&P Global Manufacturing, Services and Composite PMI readings. As investors prepare for the Fed’s 28 October monetary policy decision, the release could spark volatility in both the US Dollar and EUR/USD.
Should the report exceed expectations, markets could become more confident of further Fed rate increases over the coming months. US Treasury yields and the US Dollar would likely benefit, potentially leaving EUR/USD under pressure.
By contrast, concerns over the durability of US growth could intensify if business activity slows more sharply than forecast, especially in services. Disappointing PMIs could prompt investors to reconsider the prospect of additional monetary tightening, weighing on the Greenback while lending support to EUR/USD.
A release broadly in line with forecasts, however, might elicit only a fairly muted market response: manufacturing and services activity are both expected to remain comfortably in expansionary territory.
With markets already largely pricing in another Fed rate increase in December, Friday’s PMIs will be examined closely for confirmation of US economic resilience or evidence of a slowdown. Results above forecasts could strengthen expectations of further tightening. Weaker readings, on the other hand, could raise questions about the strength of growth and put pressure on the US Dollar.
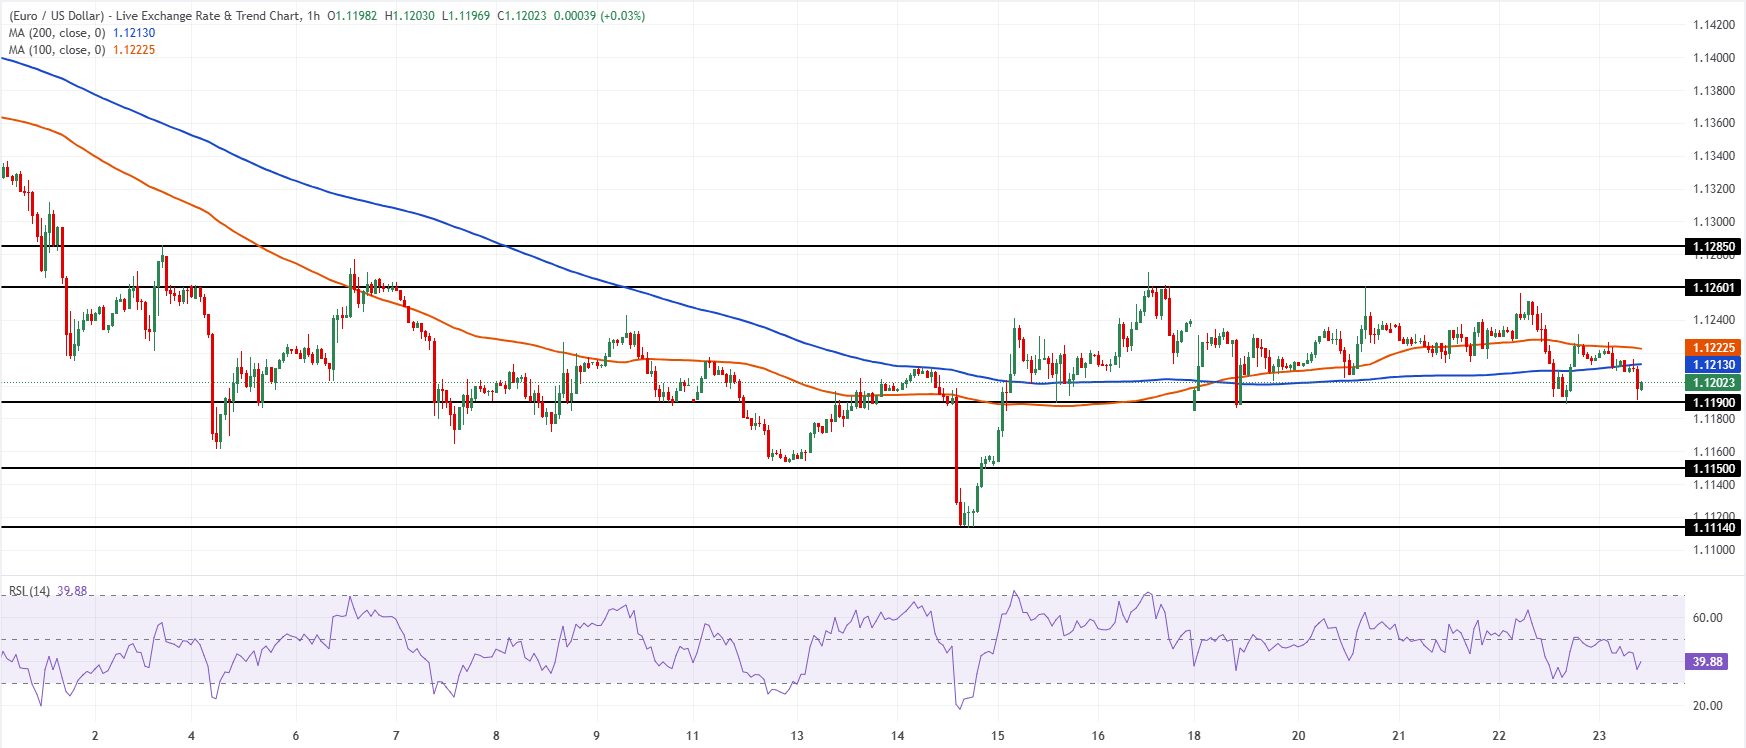
Trading below its 100-period Simple Moving Average (SMA) at 1.1223 and 200-period SMA at 1.1213, EUR/USD retains a mildly bearish tone on the one-hour chart. The pair is edging along just above nearby price support. At around 40, the Relative Strength Index (14) points to fading bullish momentum rather than outright oversold conditions, leaving downside risks in place while these moving averages limit advances.
The horizontal area around 1.1190 provides the first downside support, with further support at 1.1150 and 1.1114. Above the market, the 200-period SMA at 1.1213 forms the nearest resistance, ahead of the 100-period SMA at 1.1223. A recovery through the more substantial barriers at 1.1260 and 1.1285 would be needed to temper the prevailing bearish bias.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
As well as being the official currency of the United States of America, the US Dollar (USD) serves as the ‘de facto’ currency in a significant number of other countries, circulating alongside their local banknotes. No other currency is traded more heavily worldwide. According to 2022 data, it accounts for over 88% of global foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion. The USD replaced the British Pound as the world’s reserve currency after the Second World War. Gold backed the US Dollar for most of its history, until the Bretton Woods Agreement in 1971 brought an end to the Gold Standard.
Monetary policy, set by the Federal Reserve (Fed), is the single most significant influence on the US Dollar’s value. Achieving price stability by controlling inflation and promoting full employment are the Fed’s two mandates. Interest rate adjustments are its principal means of pursuing these objectives. If prices climb too rapidly and inflation exceeds the Fed’s 2% target, it raises rates, supporting the USD. Conversely, inflation below 2% or an excessively high Unemployment Rate may prompt the Fed to cut interest rates, putting pressure on the Greenback.
When conditions become extreme, the Federal Reserve can print additional Dollars and introduce quantitative easing (QE). Through QE, the Fed sharply expands the supply of credit within a financial system that has stalled. This unconventional policy is used when credit dries up because banks, fearing counterparty default, refuse to lend to one another. It is a last resort if interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, the Fed chose this approach to tackle the credit crunch. The process entails printing more Dollars to purchase US government bonds, mainly from financial institutions. The usual effect of QE is a weaker US Dollar.
Reversing that process, quantitative tightening (QT) sees the Federal Reserve cease bond purchases from financial institutions. It also refrains from reinvesting the principal received as its existing bonds mature into further purchases. QT is generally supportive of the US Dollar.
Published monthly, the S&P Global Composite Purchasing Managers Index (PMI) provides a leading gauge of US private-sector activity across manufacturing and services. Surveys of senior executives form the basis of the data. Responses are weighted to reflect each company’s size and its contribution to the total manufacturing or services output of its sub-sector. By capturing any change in the current month relative to the preceding month, the responses can foreshadow shifts in official measures including Gross Domestic Product (GDP), industrial production, employment and inflation. Ranging from 0 to 100, the index signals no month-on-month change at 50.0. Above 50, it points to broad expansion in the private economy, a bullish signal for the US Dollar (USD). Below 50, it indicates a general decline in activity and is viewed as bearish for USD.
Continue reading.Next publication: Fri 23 October 2026 13:45 (Prel)
Publication frequency: Every month
Consensus forecast: -
Previous reading: 58.4
Data source: S&P Global







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


