
News & AnalysisCareer

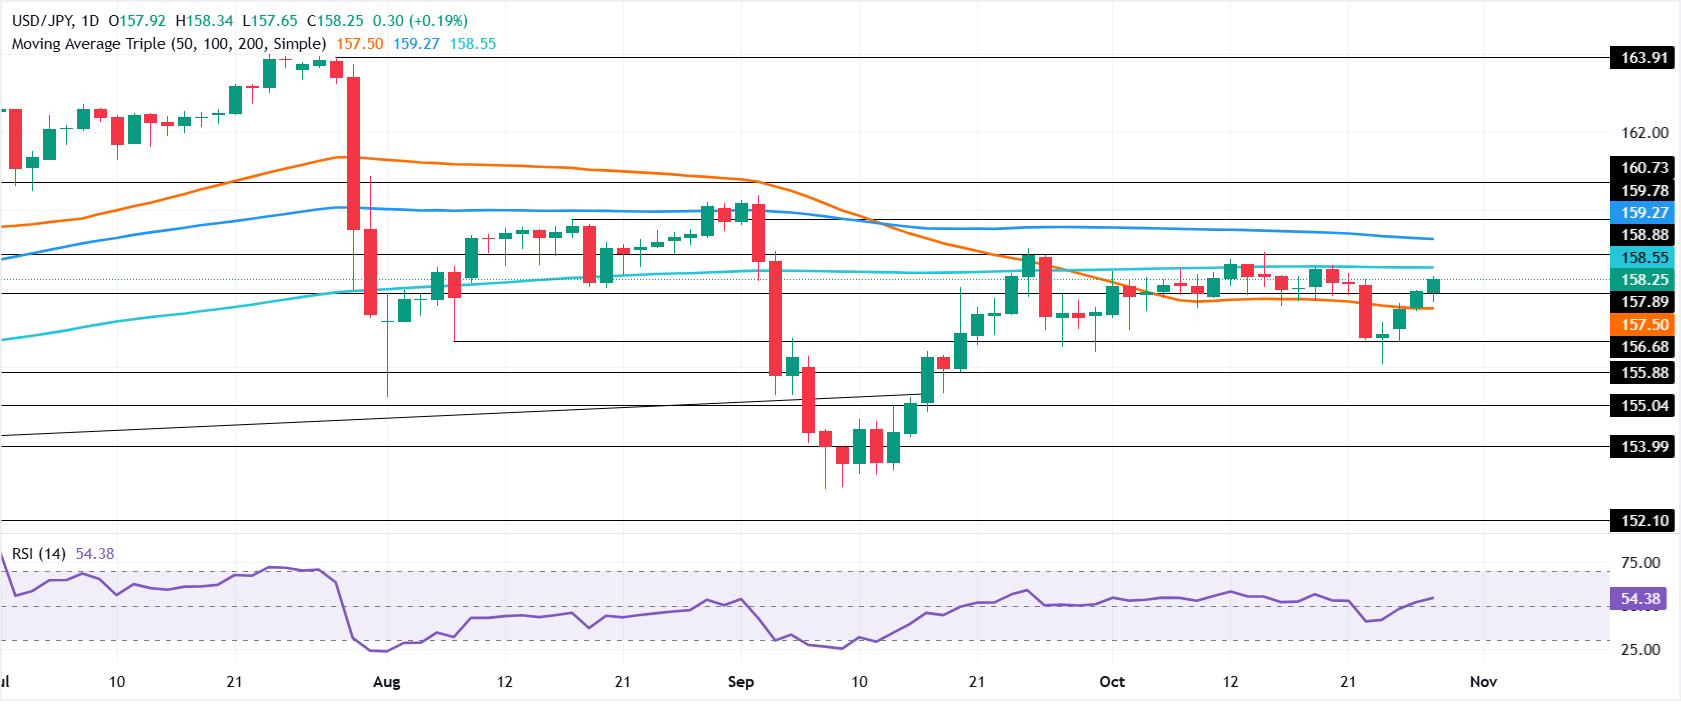
US inflation remains well above the Federal Reserve’s 2% target, but the central bank left interest rates unchanged, after which the Japanese Yen weakened against the US Dollar. Two officials dissented, preferring a quarter-percentage-point rate rise, so the decision was not unanimous. USD/JPY is trading 0.21% higher at 158.28.
Interest rates were left at 3.75%-4% by the Fed on Wednesday. The central bank recognised that economic activity is growing and that domestic spending “has been resilient, that productivity growth is strong and that capital investment is robust,” while also highlighting strong productivity growth. Turning to its employment mandate, it stated: “Job gains have kept pace with the workforce, and the unemployment rate has changed little.”
Although inflation remains elevated, according to the central bank, it opted to defer rate rises as it collects further information and evaluates the appropriate policy stance.
Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack cast the two dissenting votes on the FOMC.
Among the currencies most actively traded worldwide, the Japanese Yen (JPY) takes its broad direction from Japan’s economic performance. More specific influences include the Bank of Japan’s monetary policy, the gap between Japanese and US bond yields, and traders’ appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan’s mandate, making its actions an important influence on the Yen. Direct intervention in foreign exchange markets has occasionally been used by the BoJ, usually to weaken the currency. Such action is infrequent, however, because of political concerns among Japan’s principal trading partners. Between 2013 and 2024, increasingly divergent policies at the Bank of Japan and other major central banks meant that the BoJ’s ultra-loose monetary stance weakened the Yen against its main peers. The gradual withdrawal of that ultra-loose policy has more recently provided the Yen with some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ moved increasingly out of step with other central banks, notably the US Federal Reserve. The resulting widening in the yield gap between 10-year US and Japanese bonds favoured the US Dollar over the Japanese Yen. That gap is now narrowing as a result of the BoJ’s 2024 decision to phase out its ultra-loose policy and interest-rate cuts by other major central banks.
Investors often regard the Japanese Yen as a safe haven, drawn to its perceived reliability and stability when markets come under strain. They are therefore more likely to move money into the currency during periods of stress. Such turbulence is likely to lift the Yen against currencies viewed as riskier investments.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved

