
News & AnalysisCareer

With US interest rates left unchanged at the October meeting, the Federal Reserve’s (Fed) latest policy announcement keeps a December increase firmly in contention, weighing on Gold (XAU/USD) on Thursday. Attention now shifts to US Personal Consumption Expenditures (PCE) inflation figures for further indications of the policy path. XAU/USD stands at around $4,030 at the time of writing, a daily decline of 0.88%.
A 10-2 vote by the Federal Open Market Committee (FOMC) on Wednesday kept rates at 3.75%-4.00%, with Governor Lisa Cook and Cleveland Fed President Beth Hammack preferring a 25-basis-point rise. Despite growing evidence of inflationary pressure, the Committee opted to pause. Markets initially interpreted the decision as mildly dovish: Gold advanced, while the US Dollar and shorter-dated Treasury yields fell.
The broader tone, however, was still hawkish. Reaffirming his commitment to achieving price stability, Chair Kevin Warsh said that “while overall financial conditions are tighter, I’m unwilling and unable to call them tight.” He also emphasised that the fight against inflation did not hinge on a specific date or an individual economic release.
Although policy was held steady, Rabobank analysts note that the Committee “indicated a need for more information to help determine the appropriate policy stance.” The Fed’s data-dependent approach was reinforced by Chair Warsh’s observation that the “FOMC will receive a lot more data in the weeks through the next meeting,” underscoring the role of incoming figures in shaping its response.
In the assessment of Rabobank’s US strategist, “without providing forward guidance, Warsh essentially made the case for a rate hike in December,” implying that further tightening remains very much an option.
According to the CME FedWatch Tool, market pricing currently assigns around an 80% probability to a December rate increase. Due at 12:30 GMT, the Fed’s preferred inflation measure will test those expectations, with the advance estimate of third-quarter Gross Domestic Product (GDP) released at the same time.
After falling the previous day, the US Dollar Index (DXY) remains firmly above 102.00 as markets await the figures. The index measures the Greenback against a basket of six major currencies.
Further interest-rate increases would raise the opportunity cost of owning non-yielding Gold, leaving the prospect of additional tightening as a significant headwind. Should PCE exceed expectations, December rate-rise bets could strengthen and weigh further on Gold. Softer data, by contrast, could temper those expectations and leave room for a short-term recovery.
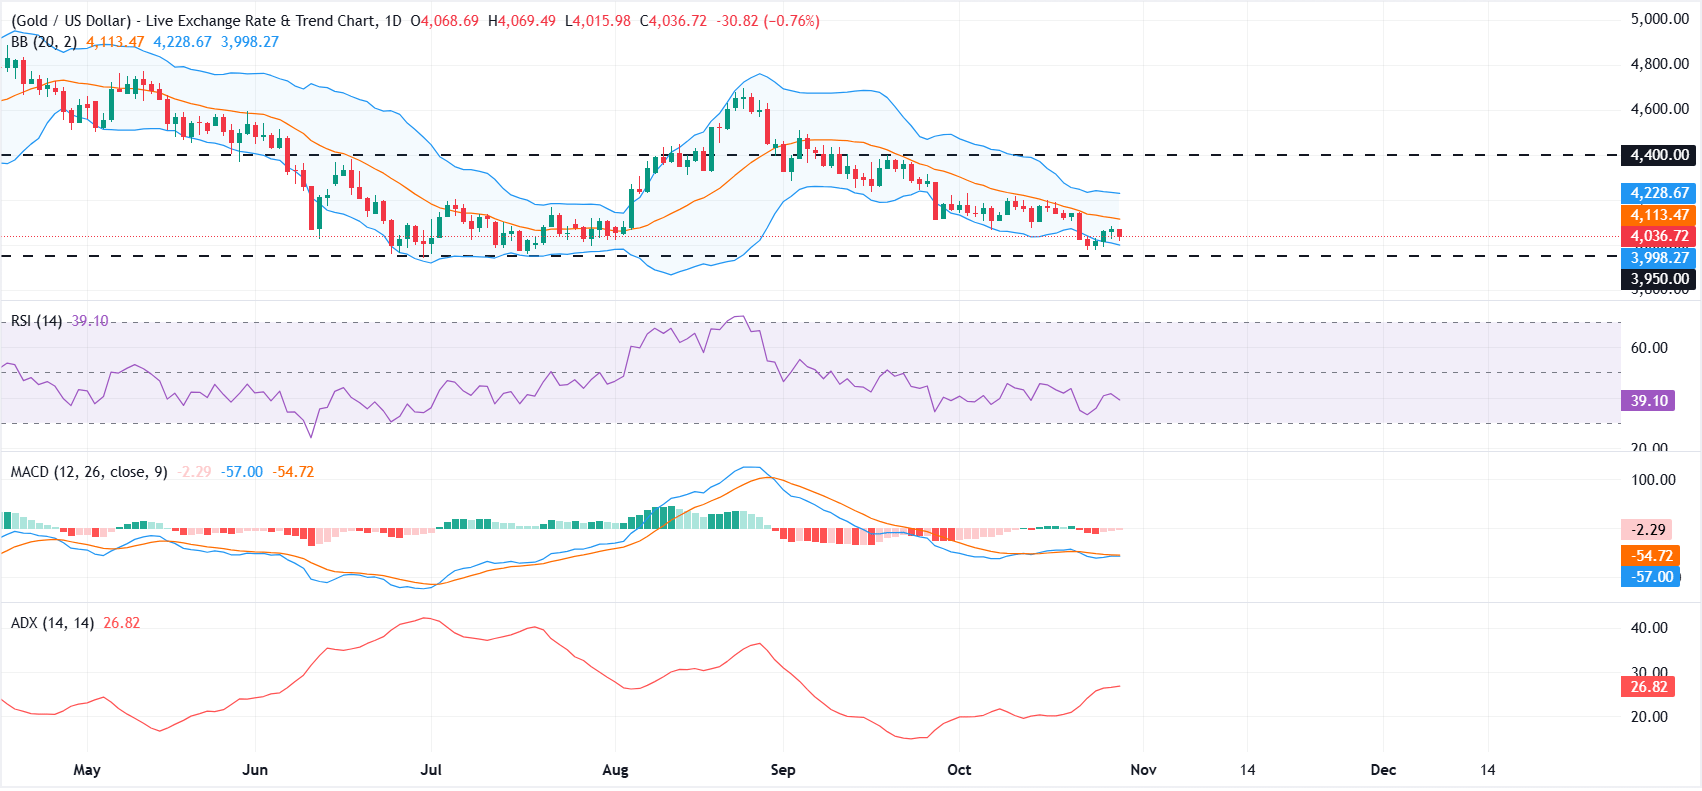
A bearish near-term bias persists on the daily chart, where XAU/USD trades beneath the 20-day Simple Moving Average (SMA) at $4,113, also the middle Bollinger Band. At around 38, the Relative Strength Index (RSI) indicates subdued buying momentum but has not entered oversold territory. Sellers also retain the advantage indicated by the Moving Average Convergence Divergence (MACD), which is still marginally negative.
Any recovery would first face the 20-day SMA around $4,113, with the upper Bollinger Band at $4,229 providing the next resistance. Holding above both levels could clear a path towards $4,400.
Further losses are likely to be contained by the lower Bollinger Band around $3,998 and the former support area near $4,000-$3,950. A clear break beneath this zone, however, could set off a more pronounced decline.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Throughout human history, Gold has served extensively as both a store of value and a medium of exchange, giving it an important role. Beyond its lustre and use in jewellery, the precious metal is now widely regarded as a safe-haven asset, or an investment considered attractive in unsettled times. Its independence from any particular issuer or government also underpins the widespread view of Gold as a hedge against inflation and currency depreciation.
The largest holders of Gold are central banks. To support their currencies during periods of turbulence, they typically diversify reserves and purchase Gold, strengthening perceptions of their economies and currencies. Substantial Gold holdings can help foster confidence in a country’s solvency. World Gold Council figures show that central banks increased their reserves by 1,136 tonnes in 2022, worth around $70 billion, the largest annual purchase since records began. Emerging-economy central banks, including those of China, India and Turkey, are rapidly expanding their Gold reserves.
Both the US Dollar and US Treasuries, major reserve and safe-haven assets, have an inverse correlation with Gold. A weakening Dollar typically accompanies a rise in Gold, allowing investors and central banks to diversify their holdings in turbulent periods. The metal also tends to move in the opposite direction to risk assets: stock market gains generally weigh on Gold prices, whereas selling in riskier markets usually supports the precious metal.
Many factors can influence Gold prices. Its safe-haven appeal means geopolitical unrest or concerns about a severe recession can quickly drive prices higher. Because Gold pays no yield, lower interest rates generally support it, while a higher cost of borrowing typically weighs on the metal. Nevertheless, the behaviour of the US Dollar (USD) accounts for most price movements, as Gold is quoted in dollars (XAU/USD). Dollar strength tends to restrain Gold prices; a softer Dollar, by contrast, is likely to lift them.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


