
News & AnalysisCareer

At $3,926 at the time of writing, Gold (XAU/USD) is down 0.45% on Tuesday as tensions in the Middle East remain elevated. Oil prices have pared their earlier losses, strengthening the US Dollar’s safe-haven appeal given the positive correlation between the two.
Uncertainty over the outcome of the US-Iran conflict is putting pressure on Gold, which currently has a negative correlation with West Texas Intermediate (WTI), the US crude benchmark. Among the conflicting headlines, the New York Times reported that Israeli intelligence had shared information suggesting Iran is considering using chemical weapons.
Reports earlier suggested Washington and Tehran were nearing an agreement. Iran rejected those claims, however, according to the IRIB news agency.
September’s Job Openings and Labor Turnover Survey (JOLTS) showed US vacancies increasing by 4.5% on the month, from 7.19 million to 7.5 million. The hiring rate edged up to 3.4% from 3.3%, while the total separations rate held steady at 3.3%.
Separately, the US Census Bureau reported that Factory Orders rose 1.8% MoM in September, compared with 0.3% MoM in the preceding month.
Against this backdrop, the US Dollar regained some ground after the US Dollar Index (DXY) touched an intraday low of 101.62. Measuring the currency against six peers, the DXY is now little changed at 101.78.
Alongside the pressure from the US Dollar, rising US Treasury yields are driving a sharp decline in bullion prices. The 10-year Treasury note yield is 4 basis points higher at 4.954%.
A further source of bearish pressure on XAU/USD is the increased likelihood traders assign to a December Federal Reserve (Fed) rate rise. According to the CME’s FedWatch Tool, those odds have climbed to 79%, compared with 74% a day earlier.
Citing softer demand for bars and coins, the World Gold Council cut its Gold investment growth forecast from 400 metric tonnes to 200 metric tonnes. It nevertheless lifted its forecast for central bank purchases.
The US midterm elections are also in focus for commodity traders. Prediction platforms such as Polymarket put the probability of Democrats regaining a House majority at around 95%. Their chances of taking the US Senate stand near 73%, which would give the Democrats control of both chambers.
Wednesday’s releases will also draw attention, with the ADP Employment Change report and October’s ISM Services Purchasing Managers’ Index (PMI) both on the agenda.
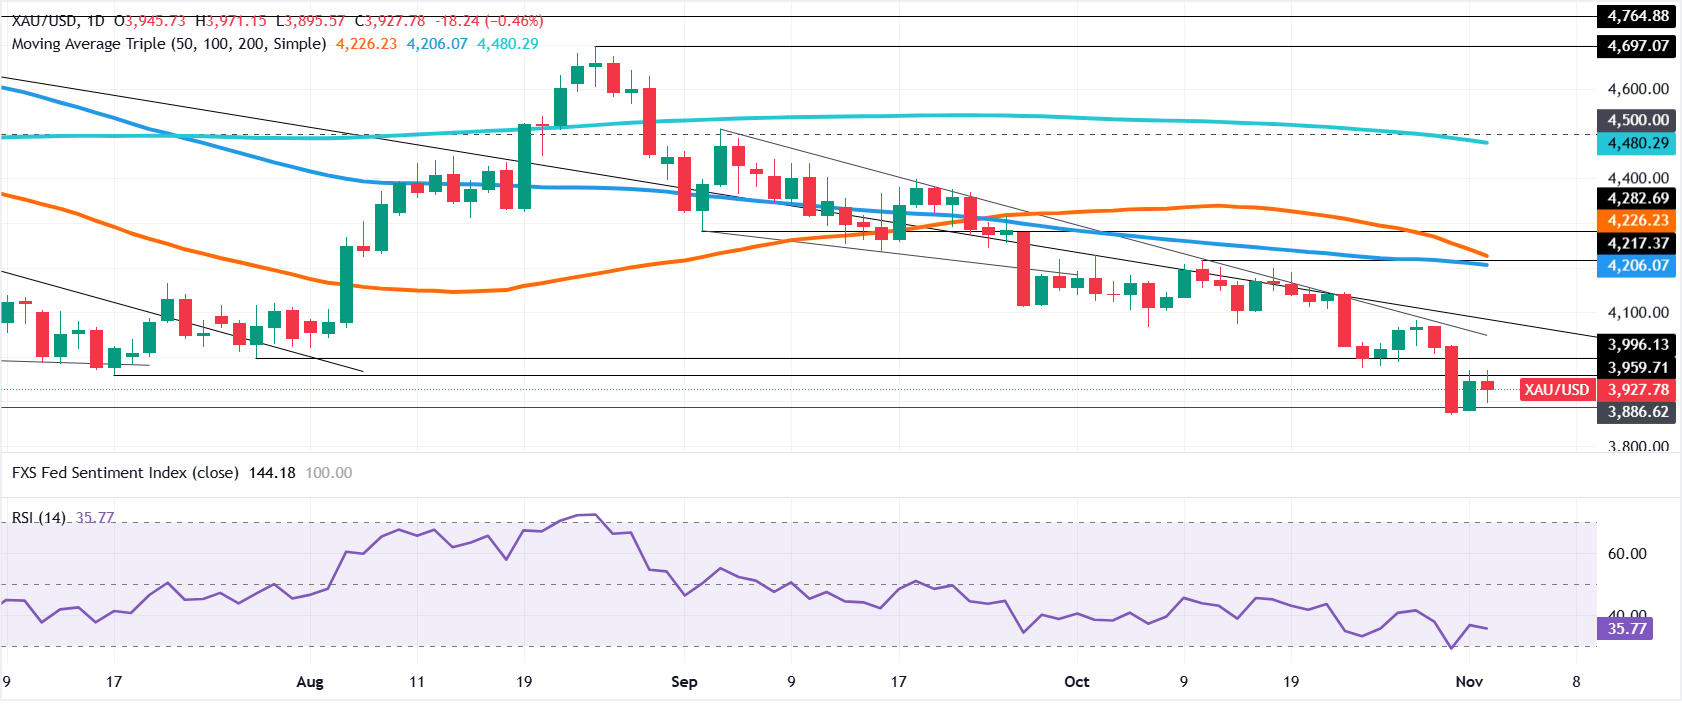
Although XAU/USD has pulled back following Monday’s gains, it has yet to set a lower low, suggesting the market remains rangebound. The Relative Strength Index (RSI), however, shows momentum drifting lower into bearish territory, pointing to further near-term downside.
A break below $3,900 would leave Gold poised to test the year-to-date low of $3,879 set on 30 October. Beyond that lies $3,500, the daily high from 22 April 2025, which has since become support.
Conversely, a recovery above $4,000 by buyers would open up a test of the key resistance trendline around $4,050-$4,070, with $4,100 the next level to watch.
Throughout human history, Gold has served widely as both a store of value and a medium of exchange, giving it an important role. Beyond its lustre and use in jewellery, the precious metal is now widely regarded as a safe-haven asset and therefore a good investment in unsettled times. Its independence from any particular issuer or government also underpins its widespread appeal as a hedge against inflation and currency depreciation.
The largest holders of Gold are central banks. To support their currencies during periods of turbulence, they typically diversify their reserves and purchase Gold, strengthening perceptions of both their economies and currencies. Substantial Gold reserves can bolster confidence in a country’s solvency. World Gold Council data show that central banks increased their reserves by 1,136 tonnes of Gold, valued at around $70 billion, in 2022. That was the largest annual purchase since records began. Emerging-economy central banks, including those in China, India and Turkey, are expanding their Gold reserves rapidly.
Both the US Dollar and US Treasuries are major reserve and safe-haven assets, and Gold is inversely correlated with them. A weaker Dollar typically supports Gold, allowing investors and central banks to diversify their holdings during turbulent periods. The metal also tends to move in the opposite direction to risk assets: stock market rallies generally weigh on Gold prices, whereas selling in riskier markets usually supports the precious metal.
A broad range of influences can move Gold prices. Its safe-haven role means geopolitical instability or concerns about a severe recession can quickly send prices higher. Because Gold pays no yield, lower interest rates tend to support it, while a higher cost of borrowing generally weighs on the metal. Most price movements nevertheless depend on the direction of the US Dollar (USD), as Gold is quoted in dollars (XAU/USD). Dollar strength usually restrains Gold prices; a weaker Dollar, by contrast, is likely to lift them.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


