

Trading
Explora una amplia gama de mercados con precios competitivos, liquidez profunda y herramientas de trading avanzadas.
Más información 
Plataforma
Opera sin interrupciones con la potente plataforma de TMGM, diseñada para ofrecer velocidad, precisión y una experiencia de trading superior.
Más información Plataforma de trading
Herramientas de trading
Academia
Aprende los fundamentos del trading con recursos ideales para principiantes, incluidas guías, seminarios web y análisis del mercado.
Más información Academia TMGM
Noticias y análisis
Obtén actualizaciones del mercado en tiempo real y análisis de expertos para adelantarte a las oportunidades de trading
Más información Noticias y análisis
Acerca de
Descubre qué distingue a TMGM: nuestra presencia global, solidez regulatoria y compromiso con la innovación en el trading.
Más información Por qué elegir TMGM
Indian Rupee gains for fifth straight day against US Dollar
- The Indian Rupee extends its advance against the US Dollar as the latter underperforms.
- Fed’s Warsh stresses price stability and AI-driven demand.
- The INR’s strength on the back of RBI’s measures could turn out to be short-lived.
The Indian Rupee (INR) continues to outperform the US Dollar (USD) on the back of weakness in the Greenback and forceful Reserve Bank of India’s (RBI) measures to curb the US Dollar’s demand by Oil Marketing Companies (OMCs).
In the opening trade on Friday, the USD/INR pair posts a fresh over five-week low at 94.69. In the Asian session, the US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, posts a fresh 10-day low near 101.80.
The US Dollar extends its weakness on Friday, following remarks from Federal Reserve (Fed) Chair Kevin Warsh at the Fireside Chat with International Monetary Fund (IMF) Managing Director Kristalina Georgieva, in which he stressed achieving price stability, surging investment, and Artificial Intelligence (AI)-led structural growth.
Warsh flags investment surge and AI risks as Fed keeps options open into year-end
Fed Chair Warsh’s speech scores 5.6/10 on the FXS Speechtracker, modestly softer relative to the historical average of 6.1/10, reflecting a cautious tone despite upbeat comments on structural growth and an investment surge. The admission of being “over-scarred from the global financial crisis” underscores a bias toward vigilance on financial stability and tail risks, even as Warsh stresses that recent developments have broadly matched the Fed’s expectations and that key policy decisions will crystallize at the October and December meetings. Warsh’s focus on AI as a demand-side force and on field hearings and task forces signals an effort to build new intellectual capital before committing to a clearer policy path, keeping Dollar traders attentive to incoming data on output, employment, and inflation.
The FXS Fed Sentiment Index was unchanged, moving 0.00 points to a still-elevated level of 127.51, consistent with hawkish territory despite the slightly softer speech score on the FXS Speechtracker. The lack of index movement suggests that Warsh’s remarks, while emphasizing caution and uncertainty around AI and tail risks, did not materially shift market perceptions of the Fed’s underlying hawkish stance into the remaining 2026 meetings.
As usual, Fed Chair Warsh has not delivered any meaningful remarks on the monetary policy outlook. Warsh has already stated explicitly that “so-called forward guidance” is not appropriate in the current scenario.
Meanwhile, financial markets remain confident that the Fed will leave interest rates unchanged at the October meeting, but will hike them in December, according to the CME FedWatch tool.
This week, the major trigger for a significant appreciation in the Indian currency remains RBI’s measures to curb the demand of the US Dollar. However, market experts doubt the sustainability of INR’s strength.
RBI steps steady INR but OCBC warns rebound may prove fleeting
Strategists at OCBC highlight that RBI’s measures of limiting access to certain INR non-deliverable derivatives to hedging purposes, extending the 20% cash reserve requirement to banks’ own qualifying FX hedges, and the special USD window for oil companies are merely a shift in demand of the currency from the spot market rather than a reduction in India’s underlying US Dollar requirements.
OCBC concludes that “we may still see room for some near-term INR gains, but the sustainability of the move will depend on whether portfolio outflows moderate and external pressures from oil prices and US yields ease.” For now, they judge that the latest policy steps “may help establish a firmer near-term footing for INR, rather than mark a decisive reversal in its broader depreciation trend.”
USD/INR Technical Analysis
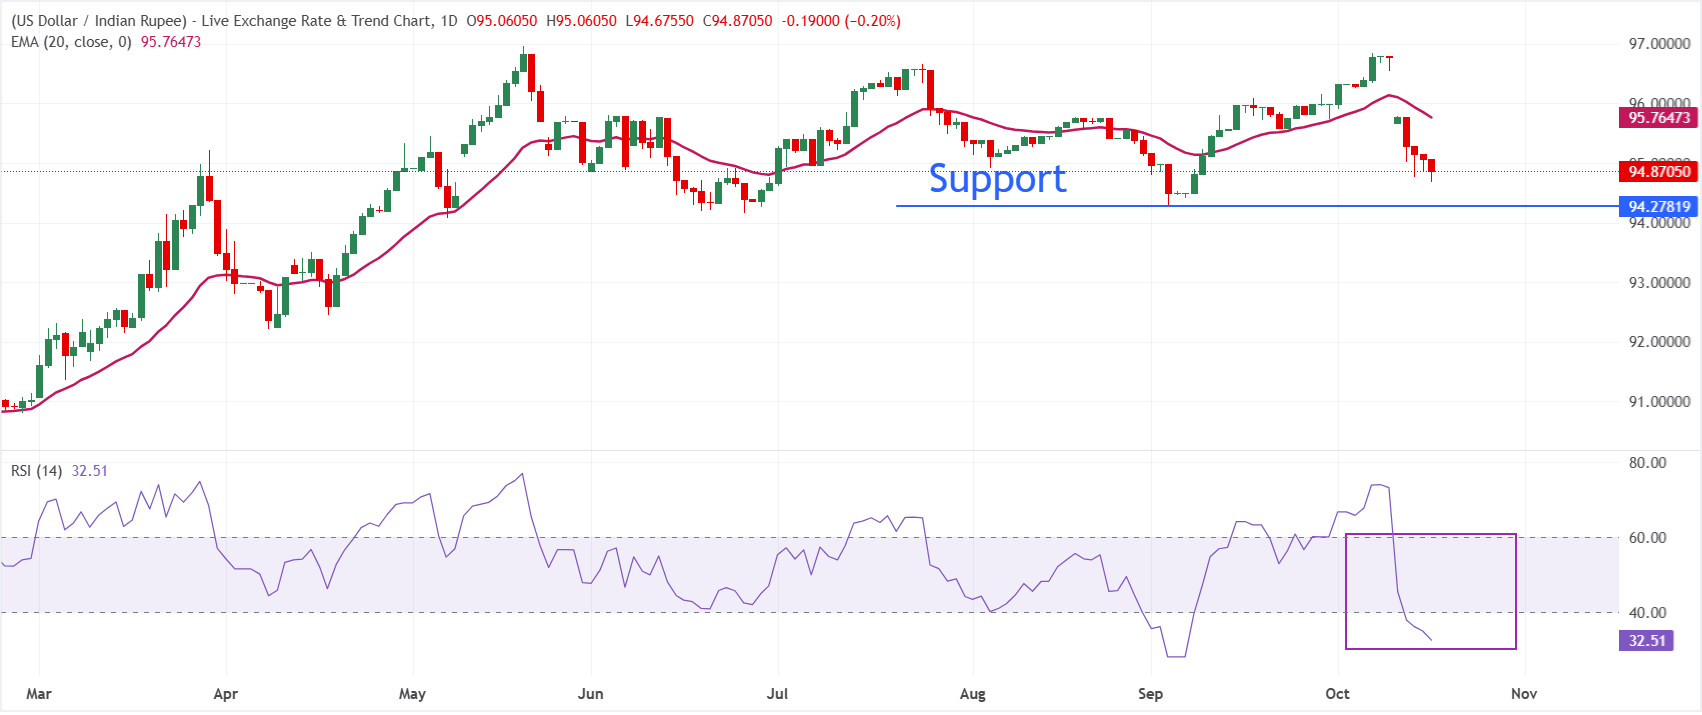
In the daily chart, USD/INR trades below 95.00, keeping a bearish near-term bias as it remains below the 20-period exponential moving average (EMA) at 95.76.
The positioning under this key dynamic barrier suggests the recent slide is still in play, while the Relative Strength Index (RSI) at 32.51 hovers just above oversold territory, hinting that downside momentum is slowing but not yet reversing.
On the topside, immediate resistance is located at the 20-period EMA around 95.76, where any recovery would likely face initial selling pressure. On the downside, the September 3 low at 94.29 is the key support level.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Artículos destacados
1EUR/USD Price Forecast: Euro stalls below 1.1240 with Eurozone Inflation data on tap2Silver Price Forecast: XAG/USD holds recovery near $57.60 amid weakness in US Dollar3NEAR Protocol Price Forecast: Rebound reclaims $5 amid steady ETF inflows4Swiss Franc edges lower despite weaker US Dollar, safe-haven demand5Euro: Range-trading bias after sharp rebound against US Dollar – UOB6British Pound gathers strength to near 1.3300 on Fed policy uncertainty7Indian Rupee gains for fifth straight day against US Dollar8WTI Price Forecast: Holds above $95.50, remains close to multi-week top amid bullish setup9Canadian Dollar stands firm near two-week high vs weak USD amid bullish oil prices
COTIZACIONES EN VIVO


TODO SOBRE FOREX
Margin Call Meaning: What It Is, What Triggers It and How to Avoid One
Top 15 Weakest Currencies in the World
Top 15 Strongest Currencies in the World
Is Forex Trading Halal?
Best Time to Trade Forex
Forex Trading vs Futures Trading
Forex Trading vs Stock Trading
Forex Trading vs Crypto Trading
Is Forex Trading Profitable In 2026?
¡Comience ahora!
Regístrese y acceda a los mercados globales en menos de 3 minutos

Conéctese con nosotros









Contactos
Teléfono: +61 2 8036 8388
Fax: +61 2 8036 8388
Correo electrónico: support@tmgm.com



La información proporcionada en este sitio web es únicamente de carácter general y no constituye asesoramiento financiero personal. Antes de actuar sobre cualquier información de este sitio web, debe considerar la idoneidad de la información en relación con sus objetivos, situación financiera y necesidades. Invertir en CFD y contratos de margen de FX conlleva riesgos significativos y no es adecuado para todos los inversores. Puede perder más que su depósito inicial. Usted no posee ni tiene ningún interés en el activo subyacente. Le recomendamos que busque asesoramiento independiente y se asegure de comprender plenamente los riesgos involucrados antes de operar. Es importante que lea y considere el documento de divulgación antes de adquirir cualquier producto listado en el sitio web. La información y los anuncios ofrecidos en este sitio web no están destinados al uso por parte de ninguna persona en ningún país o jurisdicción donde dicho uso sea contrario a las leyes y regulaciones locales. Los productos y servicios ofrecidos en este sitio web no están destinados a residentes de Estados Unidos, Malasia y Tailandia.
TMGM está autorizado y regulado en varias jurisdicciones.
Trademax Australia Limited, que opera como TMGM, está regulada por la Comisión Australiana de Valores e Inversiones (ASIC), AFSL n.º 436416, y está ubicada en Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Correo electrónico: support@tmgm.com.au
Trademax Global Limited, que opera como TMGM, está autorizada y regulada por la Comisión de Servicios Financieros de Vanuatu (VFSC), número de registro 40356, y está registrada en 1276, Kumul Highway, Port Vila, Vanuatu, República de Vanuatu.
Correo electrónico: support@tmgm.com
Trademax Global Markets (SE) Limited, que opera como TMGM, está autorizada y regulada por la Autoridad de Servicios Financieros (FSA) de Seychelles, con número de licencia SD224. La empresa está registrada en Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Correo electrónico: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, que opera como TMGM, está autorizada y regulada por la Comisión de Servicios Financieros de Mauricio (FSC) con licencia n.º GB22201012, y está registrada en 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauricio.
Correo electrónico: support@tmgm.com
Copyright © TMGM. Todos los derechos reservados