
News & AnalysisCareer

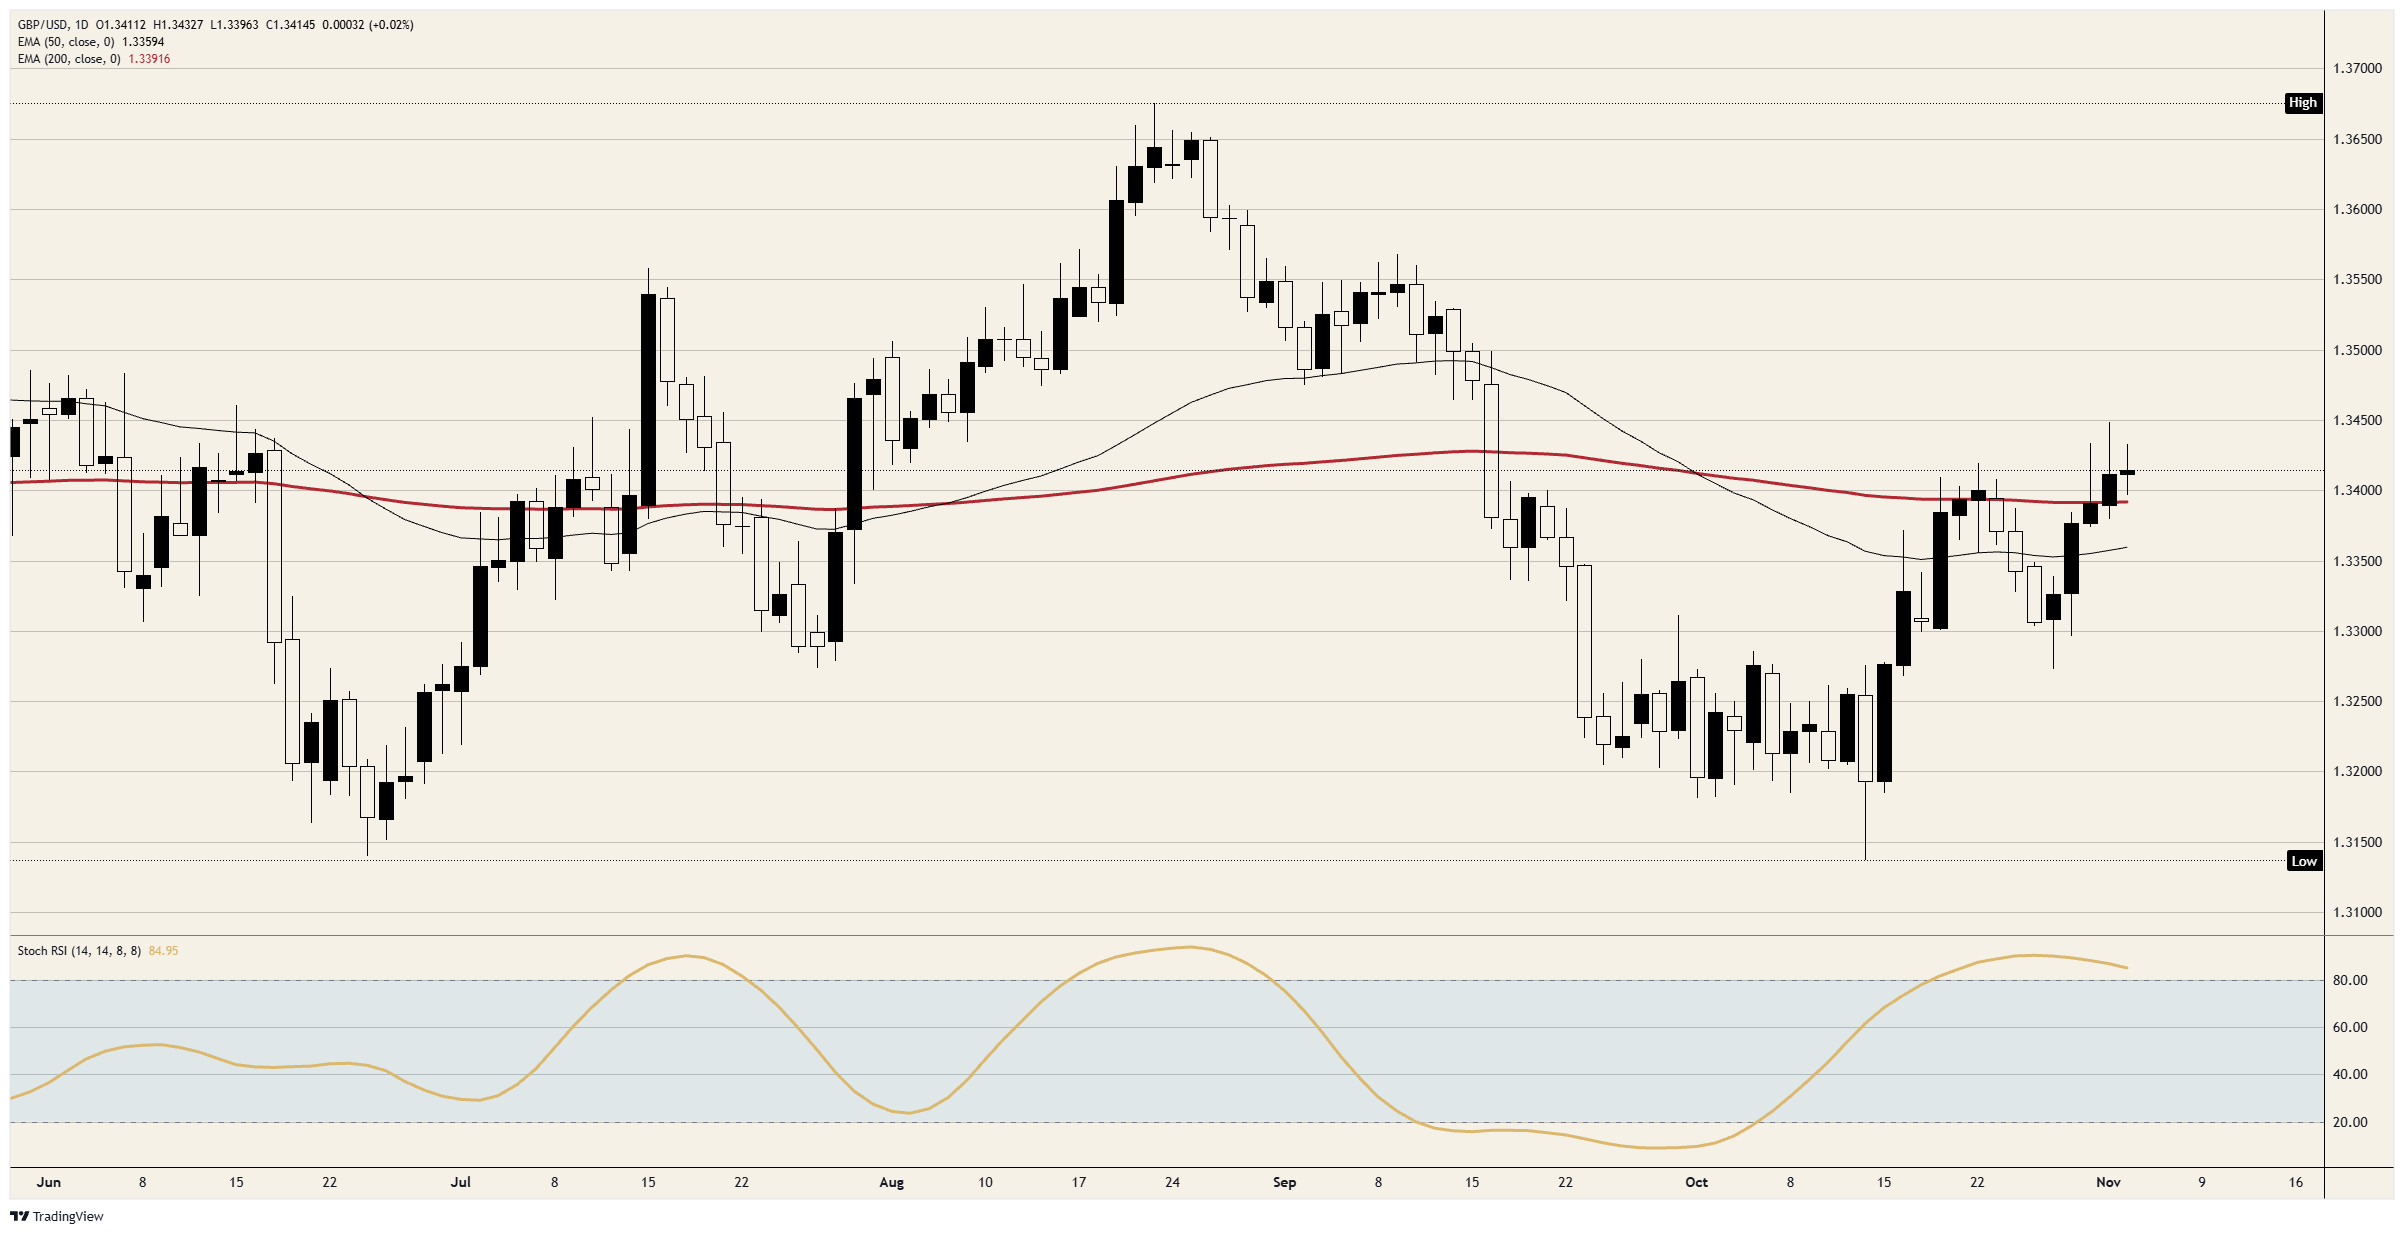
A rise in the UK’s Bank Rate from 3.75% to 4.00% is expected from the Bank of England (BoE) on Thursday, with money markets pricing in three further increases thereafter. Meanwhile, GBP/USD is heading for a fifth consecutive gain, trading just above 1.3400 and its 200-day Exponential Moving Average (EMA). Any further support for the Pound from Thursday’s meeting rests on the guidance rather than the rate decision itself.
At the September 17 meeting, Chief Economist Pill and external members Greene and Mann were the three members of the BoE’s nine-strong committee who backed a rate rise. Although BoE Governor Bailey and Deputy Governors Breeden, Lombardelli and Ramsden opted to hold, they said persistently high energy costs could make a stronger case for an increase. The forecast depends on those four changing their votes. If delivered, the rise would be the BoE’s first since August 2023.
A continued preference for unchanged rates from external members Dhingra and Taylor underpins BBH’s 7-2 forecast. Nomura, by contrast, anticipates another 6-3 split, but with the six now backing the opposite outcome. A smaller majority for a rise could suggest less willingness to deliver the three subsequent increases priced in by markets, expectations that have supported GBP/USD’s advance.
Four quarter-point increases by September 2027 are fully reflected in money-market pricing, LSEG data show, implying a Bank Rate of 4.75%. A Thursday rise is expected by 27 of 30 research houses. Most of those foresee a further increase in February before rates peak at 4.25%. In contrast, BMO’s Mark McCormick anticipates a single rise, while ING has described market pricing as extreme.
Despite Governor Bailey’s warning that unconditional commitments on future rates are inappropriate, markets have priced in a year of increases without such a pledge. According to BBH, the guidance could challenge the full point of tightening priced over the next 12 months, limiting the Pound’s upside. Should the Monetary Policy Report favour a February increase followed by a pause, some of those expectations could unwind, likely pushing GBP/USD lower.
September’s US job openings reached 7.523 million, above the 7.13 million forecast, while factory orders increased by 1.8%, exceeding expectations of 1.2%. Minutes before these releases, GBP/USD had set its session high just below 1.3450; it has remained beneath that level since. Earlier, on October 28, the Fed kept its rate at 3.75%-4.00%, with Fed Governor Cook and Cleveland Fed President Hammack dissenting in favour of a quarter-point increase.
Reports of progress in US-Iran negotiations sent Brent down towards $104 a barrel, following a statement from Iran’s negotiating team that there had been no new development. Much of September’s upside inflation surprise, which took UK inflation to 3.5%, came from petrol and diesel. Lower Brent prices offer the one route by which the case for BoE tightening could weaken before Thursday without a vote being cast.
At 12:00 GMT on Thursday, the BoE will release its decision, minutes and Monetary Policy Report, followed by Governor Bailey’s remarks at 12:30 GMT. Cleveland Fed President Hammack is scheduled to speak at 13:50 GMT. As one of October’s two dissenters, she will be speaking 110 minutes after the BoE has voted on the increase she favoured for the US. On Friday, Chief Economist Pill will brief businesses.
Before that, Wednesday brings the US Automatic Data Processing (ADP) private employment figure at 13:15 GMT, with a slowdown to 69K from 90K forecast. At 15:00 GMT, the Institute for Supply Management (ISM) services survey is expected to register 54.8, following 54.9. Attention then turns to Friday’s Nonfarm Payrolls (NFP), due at 13:30 GMT: forecasts point to 65K after 29K and an unemployment rate of 4.2%. All these releases will inform the Fed’s December decision, shaping the Dollar side of the interest-rate differential behind GBP/USD.
Results from the midterm elections begin arriving on Wednesday. Prediction markets put the likelihood of Democrats taking the Senate at close to 75%, and Reuters reported that traders were avoiding large Pound positions ahead of the results. Friday also brings speeches from New York Fed President Williams at 09:30 GMT and Fed Vice Chair for Supervision Bowman at 17:15 GMT, before and after payrolls respectively.
Resistance: Just below 1.3450, Monday’s peak marks GBP/USD’s highest level since September 16. Tuesday’s entire trading range sits within Monday’s range. Beyond that peak lies 1.3500, the level from which the pair retreated on September 16, when the Fed raised rates.
Support: Tuesday’s decline stopped a few pips above the 200-day EMA, which sits just below 1.3400. Further down, the October 29 trough stands at 1.3300. The October 28 low, just above 1.3250, marks the starting point of the five-session advance.
Bias: A short bias is favoured beneath 1.3450 ahead of Thursday, as market pricing implies more BoE tightening than most research houses anticipate. A daily close below the 200-day EMA would expose 1.3300, followed by 1.3250. Near 85, the daily Stochastic Relative Strength Index (Stoch RSI) is overbought and beginning to turn lower. Conversely, a daily close above 1.3450 would clear Monday’s peak and invalidate the short case.
Dating from 886 AD, the Pound Sterling (GBP) is the world’s oldest currency and serves as the United Kingdom’s official currency. According to 2022 data, it ranks fourth globally by foreign exchange (FX) trading activity, representing 12% of all transactions with an average daily value of $630 billion. Among its main trading pairs, GBP/USD, known as ‘Cable’, represents 11% of FX activity. GBP/JPY, which traders call the ‘Dragon’, accounts for 3%, while EUR/GBP represents 2%. Responsibility for issuing the Pound Sterling lies with the Bank of England (BoE).
Monetary policy set by the Bank of England is the most important single influence on the Pound Sterling’s value. In making its decisions, the BoE assesses progress towards its central objective of “price stability”, meaning a steady inflation rate of around 2%. Interest-rate adjustments are its main means of achieving that objective. Faced with excessive inflation, the BoE seeks to curb it by increasing interest rates. Borrowing then becomes more expensive for households and businesses. GBP generally benefits, since higher rates make the UK a more appealing destination for international investors’ funds. Inflation that is too low, by contrast, signals slowing economic growth. The BoE may then consider cutting rates to reduce borrowing costs, encouraging businesses to take out loans for projects that generate growth.
By providing a measure of economic health, data releases can affect the Pound Sterling’s value. GDP, Manufacturing and Services PMIs and employment figures are among the indicators capable of moving GBP. Sterling benefits from economic strength, which attracts overseas investment and may also prompt the BoE to raise interest rates, directly strengthening GBP. Weak economic figures, on the other hand, are likely to weigh on the Pound Sterling.
The Trade Balance is another important release for the Pound Sterling. Over a specified period, it measures the gap between a country’s export earnings and its spending on imports. Strong foreign demand for a country’s exports creates additional demand for its currency as overseas buyers purchase those goods. A positive net Trade Balance therefore supports the currency, whereas a negative balance has the opposite effect.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


