
News & AnalysisCareer

At around 1.1210 against the US dollar in Monday’s European session, the euro (EUR) retains a modest gain despite surrendering part of its earlier advance. The currency is also trading higher against its other peers.
Today’s percentage moves in the euro (EUR) against the major currencies listed are set out below. Its largest gain was against the Japanese yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.08% | 0.15% | 0.28% | 0.06% | -0.04% | 0.12% | 0.09% | |
| EUR | 0.08% | 0.27% | 0.35% | 0.13% | 0.05% | 0.22% | 0.18% | |
| GBP | -0.15% | -0.27% | 0.08% | -0.13% | -0.22% | -0.05% | -0.10% | |
| JPY | -0.28% | -0.35% | -0.08% | -0.20% | -0.32% | -0.14% | -0.18% | |
| CAD | -0.06% | -0.13% | 0.13% | 0.20% | -0.12% | 0.08% | 0.04% | |
| AUD | 0.04% | -0.05% | 0.22% | 0.32% | 0.12% | 0.18% | 0.14% | |
| NZD | -0.12% | -0.22% | 0.05% | 0.14% | -0.08% | -0.18% | -0.04% | |
| CHF | -0.09% | -0.18% | 0.10% | 0.18% | -0.04% | -0.14% | 0.04% |
Percentage movements between the major currencies are displayed in the heat map. Select the base currency in the left-hand column and the quote currency in the top row. Selecting the euro on the left and following that row across to the US dollar, for instance, gives the percentage change for EUR (base)/USD (quote) in the corresponding cell.
Moody’s decision to retain France’s Aa3 sovereign rating, rather than downgrade it as expected, is drawing buyers to the euro.
According to analysts at Danske Bank, Moody’s late-Friday decision to reaffirm France’s Aa3 sovereign rating with a negative outlook defied "wide market expectations of a downgrade." The analysts say the agency’s position relies on the assumption "that a deficit-reducing 2027 budget will be adopted and that financing costs and social tensions will abate somewhat in the coming months."
As Danske Bank notes, Moody’s now "expects a deficit of 5.2% of GDP next year, down from the 5.4% the government expects this year but slightly above its 5% target."
Although Moody’s left the sovereign rating at Aa3, it cautioned that social unrest "could constrain fiscal consolidation efforts," while unrest persisted over the weekend, though more peacefully than the previous week. Unions have already called a nationwide strike for 5 November.
Attention on monetary policy now turns to Wednesday’s announcement from the Federal Reserve (Fed), followed by the European Central Bank (ECB) on Thursday.
With both central banks expected to keep interest rates at their existing levels, market participants will scrutinise their policy guidance. They will also look for comments on whether energy supply shocks are beginning to feed through to wages and wider consumer prices.
In the euro area, Germany’s IFO Institute Business Climate Index has exceeded expectations, rising to 90.2 in October from September’s 89.9. Forecasts had pointed to a decline to 89.8.
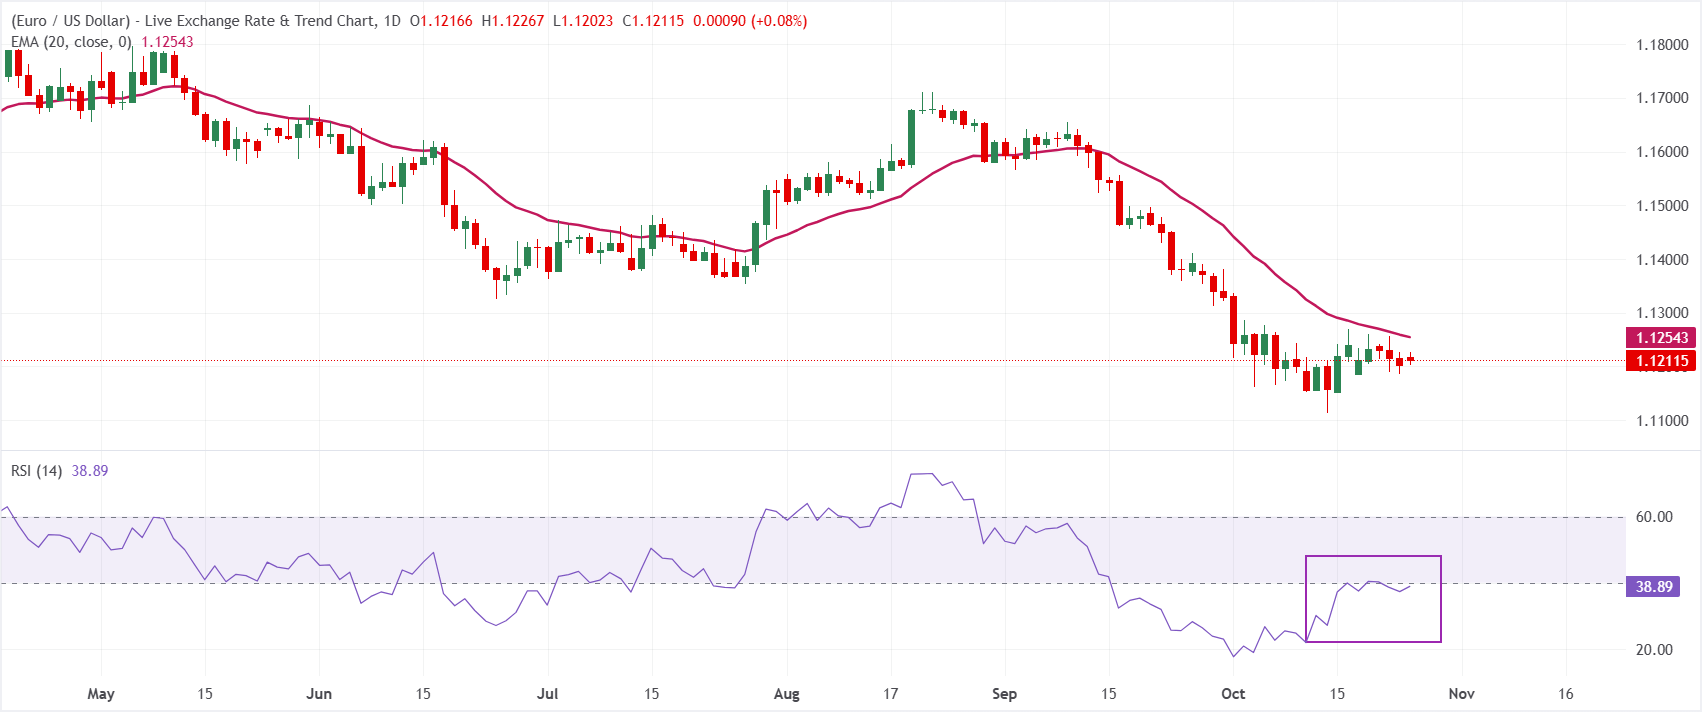
Trading near 1.1212 on the daily chart, EUR/USD remains below the 20-period exponential moving average (EMA) at 1.1254, leaving the near-term outlook bearish. Failure to regain this dynamic resistance suggests that recent declines continue to weigh on the pair. Meanwhile, the Relative Strength Index (RSI), at around 39, sits below the neutral 50 mark, pointing to limited attempts at recovery against a broadly weak backdrop.
The 20-day EMA around 1.1254 provides the first resistance on the upside. Only a sustained move above it would relieve the prevailing downward pressure and allow a more positive corrective phase to develop. With no nearby support levels mapped in the dataset, the recent lows serve as an informal floor for now. Price action is likely to remain exposed to further declines while the pair trades beneath that moving-average barrier.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
At eight scheduled meetings each year, the Federal Reserve (Fed) reviews monetary policy and decides on interest rates. Its dual mandate is to maintain full employment and keep inflation at 2%. Interest-rate setting is its principal means of pursuing those objectives, covering both the rates at which it lends to banks and those at which banks lend to one another. A rate increase generally supports the US dollar (USD) by drawing in more foreign capital. Conversely, a cut tends to weaken the USD as capital shifts towards countries offering higher returns. When rates are held steady, the focus moves to the wording of the Federal Open Market Committee (FOMC) statement: a hawkish tone signals expectations of higher interest rates ahead, while a dovish tone points to expectations of lower rates.
Continue reading.Next publication: Wed 28 Oct 2026 18:00
Release schedule: At irregular intervals
Consensus forecast: 4%
Previous reading: 4%
Data source: Federal Reserve







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


